
Lowest Price Guaranteed
Pages
423
Last Updated
August 2026
View Count
31832
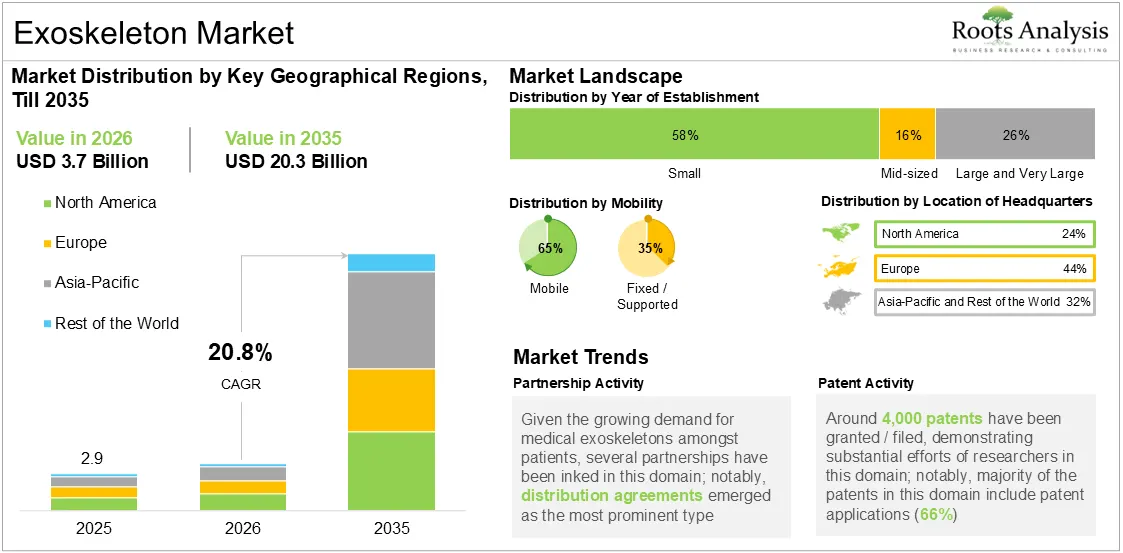
The global exoskeleton market, valued at USD 2.9 billion in 2025, is projected to reach USD 3.7 billion in 2026 and USD 20.3 billion by 2035, representing a CAGR of 20.8% during the forecast period 2026 to 2035.
To learn more about this report, request a free sample copy
The exoskeleton market is gaining relevance as mobility impairment becomes a larger clinical, social, and economic burden. Neurological conditions are now among the leading causes of disability worldwide; in 2025, the World Health Organization reported that neurological conditions affect more than 40% of the global population, representing over 3 billion people, and are responsible for more than 11 million deaths each year. This growing burden is increasing the need for rehabilitation and mobility solutions that go beyond passive support. While wheelchairs, walkers, and crutches remain important, they primarily help patients compensate for lost mobility rather than actively support functional recovery.
Exoskeletons are emerging as an important next-generation solution because they combine mobility assistance with rehabilitation-led movement training. These wearable robotic systems use sensors, motors, actuators, control software, and power units to support standing, walking, balance, and limb movement in patients with stroke, spinal cord injury, multiple sclerosis, acquired brain injury, and other neuromotor impairments. Current commercial adoption is also becoming more visible. Notably, Ekso Bionics states that its technology is used in more than 500 rehabilitation centers worldwide, while its EksoNR system is FDA-cleared for brain injury and multiple sclerosis and is the first exoskeleton cleared for both stroke and spinal cord injury.
A major recent development strengthening market access was the establishment of a Medicare reimbursement pathway for personal exoskeletons in the US. In March 2026, Lifeward reported that Aetna, Humana, and UnitedHealthcare had added Medicare Advantage coverage for the ReWalk Personal Exoskeleton, extending potential access to approximately 16 million covered individuals in the US. The company also reported that in the Q4 FY 2025 revenue from ReWalk Personal exoskeleton sales increased by 20% year-on-year, primarily due to higher reimbursed unit sales. This expansion of payer coverage is important for the market because it reduces reimbursement uncertainty, improves affordability for eligible individuals with spinal cord injuries and supports the transition of exoskeleton technology from primarily institutional rehabilitation settings toward wider personal, home, and community use.
Beyond healthcare, exoskeletons are also gaining traction in industrial and workforce-support applications, expanding the market opportunity. In April 2025, German Bionic also announced a partnership with KULR to expand AI-powered exoskeletons for the US workforce, with KULR receiving North American marketing and distribution rights. These developments indicate that exoskeletons are evolving from niche rehabilitation devices into broader wearable robotics platforms that support mobility, worker safety, rehabilitation efficiency, and long-term independence.
| Product / Platform | Company | YoE | Headquarters | Access / Regulatory Milestone |
| Atalante X | Wandercraft | 2012 | Paris, France | FDA indication extension announced in November 2025 |
| EksoNR | Ekso Bionics | 2005 | California, United States | FDA-cleared for stroke, spinal cord injury, acquired brain injury, and multiple sclerosis rehabilitation |
| Ekso Indego Personal | Ekso Bionics | 2005 | California, United States | Home and community-use personal exoskeleton for individuals paralyzed from SCI levels T3-L5 |
| HAL Lower Limb | CYBERDYNE | 2004 | Ibaraki, Japan | Medical walking exercise platform for progressive neuromuscular diseases |
| ReWalk Personal Exoskeleton | Lifeward (Formerly known as ReWalk Robotics) | 2001 | Yokneam Illit, Israel | Assigned to the Medicare brace benefit category from January 1, 2024; covered where reasonable and necessary |
| ReWalk Medicare Fee Schedule | Lifeward (Formerly known as ReWalk Robotics) | 2001 | Yokneam Illit, Israel | CMS listed a final Medicare purchase rate of USD 91,032 by state in 2024 |
| ReWalk 7 Personal Exoskeleton | Lifeward (Formerly known as ReWalk Robotics) | 2001 | Yokneam Illit, Israel | FDA clearance received in March 2025 |
Abbreviation: YoE: Year of Establishment
Based on the research, we have segmented the exoskeleton market into body part covered, mode of operation, form of exoskeleton, mobility, end user and key geographical regions.
By Body Part Covered
By Mode of Operation
By Form of Exoskeleton
By Mobility
By End User
By Key Geographical Regions
Technological advances, including lighter, more ergonomic actuation, compact sensorized joints, wireless telemetry to eliminate tethering, higher-frequency control loops for fast transient responses, and on-device analytics for real–time diagnostics and predictive maintenance, are aligning exoskeletons with the functional, safety, and usability demands of modern medical and industrial applications.
Emphasizing this shift, Gregory Galarneau (Founder, The Exoskeleton Store), stated, "Currently, the domain serves more than 250 customers. Smaller, family-run businesses with 50 employees or fewer represent a particularly promising market, as their owners and managers are more aware of workers' daily fatigue and physical pain, have simpler approval processes, and are often more willing to adopt solutions that improve employee well-being."
Discussions with multiple stakeholders in this domain have influenced the opinions and insights presented in this study. The market report includes transcripts of the following discussions:
In addition, the market report includes transcripts of the following other third-party discussions:
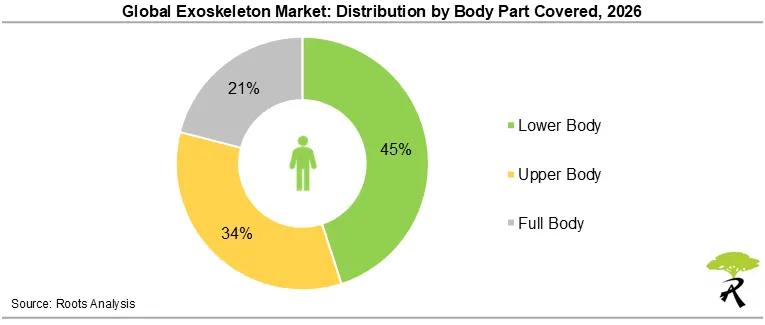
Based on the body part covered, the global exoskeleton market is segmented into upper body, lower body and full body.
Currently, lower body subsegment holds the largest share of the exoskeleton market owing to its widespread adoption in rehabilitation, mobility assistance, and industrial applications. Majority of the commercially available exoskeleton systems are designed to restore or augment lower-limb function in individuals with spinal cord injuries, stroke, multiple sclerosis, and other neurological or musculoskeletal disorders, creating a well-established clinical demand. For example, Ekso Bionics, ReWalk Robotics, and CYBERDYNE have commercialized lower-limb exoskeletons that are widely used in rehabilitation and mobility assistance.
The upper body exoskeleton segment is expected to grow at a significant pace during the forecast period owing to its increasing adoption across industrial, manufacturing, logistics, construction, and healthcare settings to reduce upper-limb fatigue and work-related musculoskeletal disorders. Rising awareness of occupational ergonomics and workplace safety is encouraging employers to deploy wearable assistive devices that support repetitive overhead tasks and manual material handling, thereby improving worker productivity and reducing injury-related costs. Furthermore, technological advancements in lightweight materials, wearable sensors, AI-assisted motion control, and ergonomic designs are enhancing the usability and comfort of upper body exoskeletons.
Based on the mode of operation, the global exoskeleton market is segmented into powered, passive and hybrid.
Currently, powered exoskeletons hold the largest share of the exoskeleton market owing to their superior functional capabilities and broader adoption across healthcare, industrial, and defense applications. Unlike passive systems, powered exoskeletons actively assist movement using electric motors, actuators, or hydraulic systems, making them the preferred choice for patients with severe mobility impairments, including spinal cord injuries, stroke, and neuromuscular disorders. The higher clinical effectiveness of powered systems has led to greater commercialization, regulatory approvals, and reimbursement support, particularly in rehabilitation settings. In addition, industrial employers are increasingly investing in powered exoskeletons to reduce worker fatigue and improve productivity in physically demanding tasks.
The hybrid mode segment is expected to grow at a significant pace during the forecast period owing to the increasing demand for exoskeletons that combine the mobility assistance of powered systems with the lightweight design and energy efficiency of passive technologies. Manufacturers are focusing on hybrid architectures that provide powered assistance only when needed, thereby reducing battery consumption while improving user comfort and extending operating time. This makes hybrid exoskeletons particularly attractive for long-duration industrial work, military operations, and rehabilitation programs where continuous powered assistance is unnecessary.
For example, companies such as Ottobock and German Bionic are incorporating intelligent sensing, adaptive control algorithms, and ergonomic designs to optimize assistance based on user movement and workload. Additionally, increasing investment in AI-integrated wearable robotics, rising demand for versatile exoskeletons across multiple end-use sectors, and ongoing product innovation are expected to accelerate the adoption of hybrid systems, supporting strong market growth during the forecast period.
Based on the form of exoskeleton, the exoskeleton market is segmented into rigid and soft exoskeletons.
Rigid exoskeletons hold the largest share of the exoskeleton market owing to their established use in medical rehabilitation, mobility assistance, and industrial load-bearing applications that require high structural support and precise motion control. These systems provide greater stability, weight-bearing capacity, and joint alignment, making them the preferred choice for patients with spinal cord injuries, stroke, and lower-limb paralysis, where substantial mechanical assistance is required. Moreover, most commercially approved powered exoskeletons currently available are rigid in design, resulting in higher market penetration across hospitals, rehabilitation centers, and industrial workplaces.
The soft exoskeleton segment is expected to grow at a significant pace during the forecast period owing to increasing demand for lightweight, flexible, and ergonomically designed wearable assistive devices that enhance user comfort without restricting natural movement. Unlike rigid systems, soft exoskeletons are easier to wear for extended periods, making them particularly attractive for industrial workers, military personnel, elderly individuals, and patients requiring long-term mobility assistance. Furthermore, advances in smart textiles, soft robotics, wearable sensors, artificial intelligence, and lightweight actuation technologies are improving the performance and commercial viability of soft exoskeletons.
For example, SUITX (now part of Ottobock) and HeroWear have developed lightweight wearable systems for occupational ergonomics, while research institutions continue to expand clinical applications for rehabilitation. In addition, the growing emphasis on workplace injury prevention, home-based rehabilitation, and wearable assistive technologies is expected to accelerate the adoption of soft exoskeletons, supporting robust market growth during the forecast period.
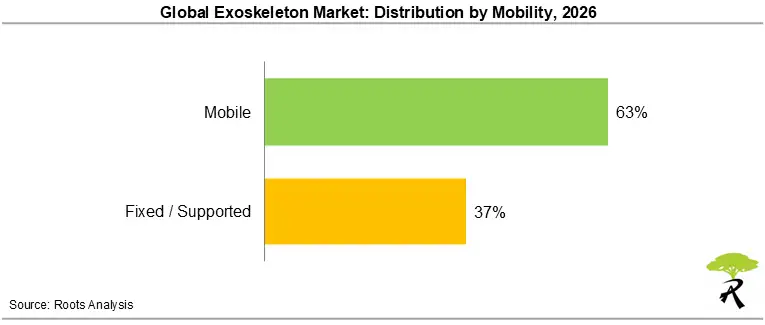
Based on mobility, the global exoskeleton market is segmented into fixed / supported and mobile.
Currently, mobile exoskeletons hold the largest share of the exoskeleton market owing to their broad applicability across rehabilitation, mobility assistance, industrial ergonomics, and defense sectors. Unlike stationary systems that are confined to clinical or laboratory environments, mobile exoskeletons enable users to perform daily activities and rehabilitation exercises in real-world settings, significantly expanding their commercial adoption. The increasing demand for wearable mobility solutions among patients with spinal cord injuries, stroke, and age-related mobility impairments, coupled with growing deployment in industrial workplaces to reduce worker fatigue and musculoskeletal injuries, has strengthened demand for mobile systems.
The mobile exoskeleton segment is expected to grow at a significant pace during the forecast period owing to continuous technological advancements that improve portability, battery life, artificial intelligence-based gait assistance, and user comfort. Manufacturers are increasingly developing lightweight, autonomous wearable systems that support long-duration use in home rehabilitation, industrial operations, and military applications, thereby expanding the addressable market beyond hospitals and rehabilitation centers.
For instance, Wandercraft has expanded its portfolio with personal exoskeleton solutions designed for everyday mobility, while German Bionic continues to advance AI-enabled mobile exoskeletons for industrial workers. Furthermore, increasing investment in wearable robotics, favorable reimbursement policies in selected markets, and expanding clinical evidence supporting long-term exoskeleton-assisted rehabilitation are expected to accelerate the adoption of mobile exoskeletons during the forecast period.
In terms of key geographical regions, the global exoskeleton market is segmented into North America, Europe, Asia-Pacific and Rest of the World.
Currently, North America holds the largest share (~45%) of the exoskeleton market owing to the region's strong commercialization ecosystem, favorable reimbursement landscape for medical exoskeletons, and substantial investments in wearable robotics across healthcare, industrial, and defense sectors. Notably, the United States has been an early adopter of robotic rehabilitation technologies, supported by increasing reimbursement for exoskeleton-assisted gait training from private insurers and the US Department of Veterans Affairs, which has expanded access to exoskeletons for veterans with spinal cord injuries.
In addition, the US Food and Drug Administration has granted multiple clearances for robotic exoskeletons, facilitating their clinical adoption in rehabilitation centers and hospitals. The presence of leading manufacturers, including Ekso Bionics, ReWalk Robotics, Sarcos Technology and Robotics Corporation, and SuitX (now part of Ottobock), has further accelerated product innovation and commercialization.
The Asia-Pacific exoskeleton market is expected to grow at a significant pace during the forecast period owing to rapid industrial automation, an aging population, rising incidence of neurological disorders, and increasing government support for robotics and rehabilitation technologies. Countries such as Japan, China, and South Korea are actively promoting the development and adoption of assistive robotics through national robotics strategies and healthcare innovation programs.
For instance, Japan's Robot Care Equipment Development and Introduction Project, supported by the Ministry of Economy, Trade and Industry (METI) and the New Energy and Industrial Technology Development Organization (NEDO), has accelerated the commercialization of rehabilitation and nursing-care exoskeletons. Similarly, China's 14th Five-Year Plan for Robot Industry Development (2021-2025) identifies rehabilitation and medical robotics as strategic growth areas, encouraging domestic innovation and manufacturing.
| Key Report Attribute | Details | |
| Historical Trend | Since 2023 | |
| Forecast Period | Till 2035 | |
| Market Size 2026 | USD 3.7 Billion | |
| Market Size 2035 | USD 20.3 Billion | |
| CAGR (Till 2035) | 20.8% | |
| Segments Covered |
|
|
| Key Players |
|
|
| PowerPoint Presentation (Complimentary) |
Available | |
| Customization Scope | 15% Free Customization | |
| Excel Data Packs (Complimentary) |
Available | |