
Lowest Price Guaranteed
Pages
270
Last Updated
January 2026
View Count
18576
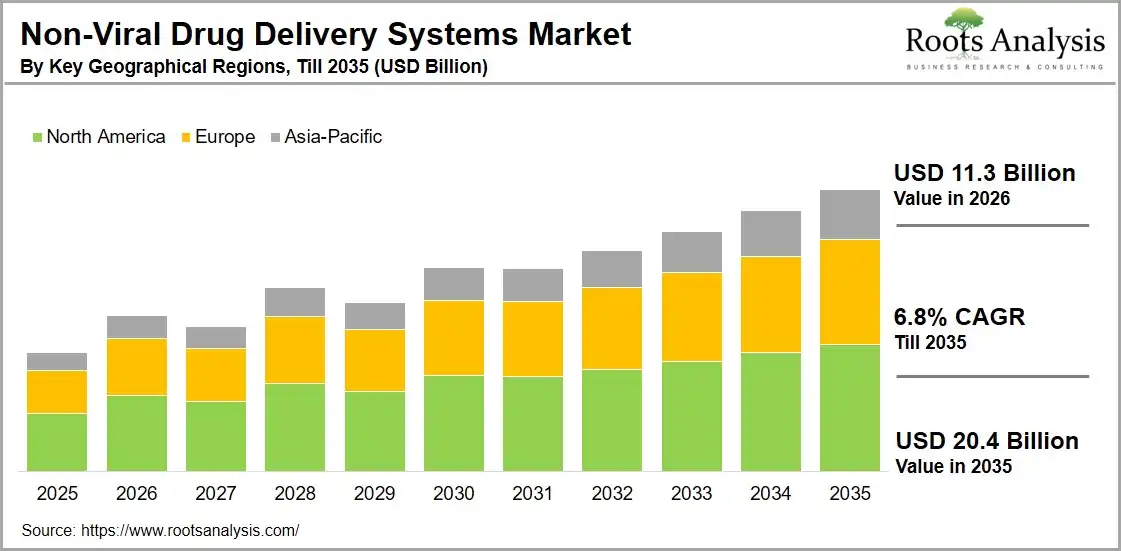
The global non-viral drug delivery systems market, valued at USD 8.6 billion in 2025, is projected to reach USD 11.3 billion in 2026 and USD 20.4 billion by 2035, with a 6.8% CAGR during the forecast period 2026 to 2035.
To learn more about this report, request a free sample copy
Non-viral drug delivery is an innovative drug delivery approach which is a potential alternative to viral vectors for the delivery of genetic material or biotherapeutics to the cells, tissues or organs. In recent years, numerous intracellular non-viral drug delivery methods have been on the rise due to the efficient delivery of drugs. The increasing number of intracellular non-viral drug delivery methods can be attributed to the benefits offered by the non-viral vectors over viral vectors; these include better safety, efficiency, specificity towards target cells and lower risk of triggering the immune system.
Overall, the use of non-viral vectors also reduces the likelihood of mutagenesis, making them a more favorable option for gene delivery. Further, the non-viral vectors can carry larger payload than viral vectors (such as AAV vectors), resulting in increased usage of these vectors in the targeted drug delivery. Notable examples of non-viral vectors include nanoparticles (especially lipid nanoparticles), cell penetrating peptides (CPP) and exosome-based drug delivery systems.
 |
 |
 |
Notably, non-viral vectors utilize specialized approaches / mechanisms in order to target the intracellular protein and enzymes. These systems generally use conjugation and / or encapsulation for enabling the targeted RNA, peptide, antibody, protein and DNA delivery into the cells. It is worth mentioning that the targeted drug delivery of a pharmacological substance (either biologics and small molecules) to its intended physiological site of action ensures that adequate concentration of the therapeutics is made available, in order to elicit the desired clinical benefits and limit off-target / systemic toxicity. In fact, recent advancements in cell biology and drug delivery systems have identified potential therapeutic targets that were previously considered incurable due to their localization within the cell membrane.
 |
 |
 |
In September 2024, NanoSyrinx raised USD 13 million in a seed funding round, in order to advance its intracellular nanosyringe technology that is aimed to target biologics to the sites that are difficult to target within the cell. As stated by Dr. Edwin Moses (Chairman of Board of Directors, NanoSyrinx), “NanoSyrinx’s technology promises to make a positive difference to the existing challenges associated with intracellular delivery of therapeutics. I am delighted to join the Board and help build on the momentum of this latest fundraise, to support the company and its leadership team in the further development of this unique platform which has the potential to create enormous value and make a real difference to patients’ lives”.
In fact, a study suggests that over 20% of the proteome, including oncogenic proteins, cell metabolism regulators, components of different signal transduction pathways and enzymes, is localized within the cell membrane. Considering the fact that only 10% of the human genome can selectively bind to small molecule pharmaceuticals, industry experts believe that intracellular therapies, particularly gene delivery, present a promising alternative to conventional therapies. Driven by the ongoing pace of innovation in the development of these technologies and the increasing demand for targeted non-viral drug delivery, the non-viral drug delivery systems market is anticipated to witness substantial market growth during the forecast period.
 |
 |
 |
The market report presents an in-depth analysis of the various non-viral drug delivery systems, across different segments, as defined in the table below:
| Key Report Attributes | Details | |
| Forecast Period | Till 2035 | |
| Market Size 2026 | $11.3 Billion | |
| Market Size 2035 | $20.4 Billion | |
| CAGR till 2035 | 6.8% | |
| Type of Molecule Delivered |
|
|
| Type of Biologic Delivered |
|
|
| Type of Vehicle Used |
|
|
| Target Therapeutic Area |
|
|
| Type of Payment Employed |
|
|
| Key Geographical Regions |
|
|
| Companies Profiled |
|
|
| PowerPoint Presentation (Complimentary) |
Available | |
| Customization Scope | 15% Free Customization | |
| Excel Data Packs (Complimentary) |
|
|
One of the key objectives of the non-viral drug delivery systems market report is to estimate the current market size, opportunity and the future growth potential of the market, over the forecast period. We have provided informed estimates on the likely evolution of the market for the forecast period.
The non-viral drug delivery systems market analysis also features the likely distribution of the current and forecasted opportunity within the market across various segments, such as distribution by type of molecule delivered (biologics and small molecules), type of biologic delivered (RNA, DNA, proteins / peptides and antibodies), type of vehicle used (nanoparticles, extracellular vesicles, polymers, oligonucleotides and cell penetrating peptides), target therapeutic area (oncological disorders, infectious diseases, cardiovascular disorders, genetic disorders, hepatic disorders, metabolic disorders, neurological disorders, pulmonary disorders, rare disorders and other disorders), type of payment employed (upfront payments and milestone payments), key geographical regions (North America, Europe and Asia-Pacific) and leading players.
In order to account for future uncertainties associated with some of the key parameters and to add robustness to our model, we have provided three market forecast scenarios, namely conservative, base, and optimistic scenarios, representing different tracks of industry’s evolution.
The opinions and insights presented in this study were influenced by discussions conducted with multiple stakeholders in this domain. The market report features detailed transcripts of interviews conducted with the following individuals:
Further, all actual figures have been sourced and analyzed from publicly available information forums and primary research discussions. Financial figures mentioned in this market report are in USD, unless otherwise specified.
Based on the type of molecule delivered, the global non-viral drug delivery systems market is segmented into biologics and small molecules. It is worth mentioning that currently, biologics segment occupies the highest share (95%) in the overall market and is expected to witness substantial market growth during the forecast period. This can be attributed to the fact that biologics have the ability to target complex biological pathways with high specificity and reduced side effects. Notably, these molecules facilitates the treatment of various diseases that were previously difficult to address with traditional drugs, often with greater efficacy and fewer adverse reactions.
The global non-viral drug delivery systems market is categorized across various types of biologic delivered, such as RNA, DNA, proteins / peptides and antibodies. Currently, amongst all these types, RNA segment occupies the largest share (65%) of the overall market. This is due to the ability of RNA molecules to target any gene in the genome, and it also plays a critical role in regulating gene expression, splicing and post-translational modifications. Further, it is worth highlighting that antibodies market segment is likely to grow at a relatively higher CAGR during the forecast period.
The global non-viral drug delivery systems market is segmented across different types of vehicle used namely, nanoparticles, extracellular vesicles, polymers, oligonucleotides and cell penetrating peptides. The current market is dominated by the revenues generated through nanoparticles and is expected to continue dominating the market, during the forecast period. This can be attributed to the fact that nanoparticles have unique size, large surface area-to-volume ratio as well as ability to be precisely engineered to target specific tissues. This allows for controlled drug release and improved efficacy compared to other delivery vehicles.
Based on the target therapeutic area, the global market is segmented across oncological disorders, infectious diseases, cardiovascular disorders, genetic disorders, hepatic disorders, metabolic disorders, neurological disorders, pulmonary disorders, rare disorders and other disorders. Currently, the oncological disorders segment is expected to hold the majority non-viral drug delivery systems market share (27%).
Further, it is worth highlighting that the infectious diseases market segment is likely to grow at a relatively higher CAGR during the forecast period. This is due to the urgent need for effective, targeted treatments against rapidly evolving pathogens. The non-viral delivery systems reach the infected tissues and deliver drugs with minimal immune response, making them particularly suitable for tackling infectious diseases.
Based on the type of payment employed, the global non-viral drug delivery systems market is segmented into upfront payments and milestone payments. It is worth mentioning that upfront payments occupy the majority share (62%) in the current market and this trend is unlikely to change in the future.
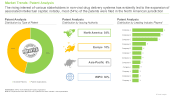
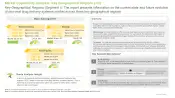
This segment highlights the distribution of overall market across various key geographies, such as North America, Europe and Asia Pacific. Presently, North America is estimated to capture majority of the non-viral drug delivery systems market share (49%), and this trend is unlikely to change in the future as well. Further, it is worth highlighting that the market in Asia-Pacific is expected to grow at a relatively higher CAGR, during the forecast period, till 2035. This can be primarily attributed to the growing ageing population, which is contributing to a rise in chronic diseases. Consequently, this surge in chronic conditions is driving the development of various non-viral drug delivery systems in the region.
The “Non-Viral Drug Delivery Systems Market: Industry Trends and Global Forecasts, till 2035” market report features an extensive study of the current market landscape, market size and future opportunities within the non-viral drug delivery systems industry, during the given forecast period. The market report highlights the efforts of several stakeholders engaged in this rapidly emerging segment of the drug delivery systems market. Key takeaways of the market report have been briefly discussed below.
The prevalence of chronic diseases has significantly increased over the years, raising serious concerns. According to the National Center for Health Statistics, in 2024, around 2 million new cancer cases and 611,720 deaths due to cancer have been reported in the US, with a significant rise in cancer rate predicted in the coming years. This alarming trend underscores the urgent need for effective non-viral drug delivery systems for cancer therapy.
However, there are several challenges associated with the treatment of cancer with respect to the target delivery of drugs, such as the heterogenicity of tumor cells and high interstitial fluid pressure inside the tumor. As a result, advanced techniques are essential for achieving targeted delivery to cancer cells and therefore revolutionizing cancer treatment.
In May 2024, researchers from Waseda University and RIKEN Institute developed a hybrid nanotube (HyNT) stamp system that can intracellularly deliver multiple proteins into the target cells. As stated by Dr. Takeo Miyake (Professor, Waseda University), “Through our innovative stamp system, we successfully delivered lactate oxidase (LOx) into both healthy mesenchymal stem cells (MSC) and cancerous HeLa cells. While MSC cells remained unaffected, we observed significant cell death in HeLa cancer cells following LOx treatment with viabilities decreasing over time. Our findings highlight the promising efficacy of intracellularly delivered LOx in selectively targeting and killing cancer cells, while sparing healthy cells, offering a targeted therapeutic strategy for cancer treatment.” Since the recommended treatment options for other chronic diseases are mostly biologics, the delivery to the target cells has to be precise in order to ensure maximum therapeutic benefit.
There are multiples techniques used for the purpose of delivering the drug to target cells. One of the techniques is non-viral drug delivery systems. Despite the various advantages associated with non-viral drug delivery systems, there are certain challenges related to the delivery of biologics with non-viral vectors. In order to deliver the drug into the cells, the non-viral vector has to interact with extracellular environment, which can cause degradation of such entities and may pose a challenge for the delivery of drugs. Further, high molecular weight of proteins and peptides becomes an issue for systemic drug distribution due to their poor membrane permeability and leads to limited absorption of drugs across biological barriers.
To address these challenges, various technology providers are focusing on the development of technology platforms to enhance the efficacy of biologics via non-viral vectors.
Interestingly, the stakeholders are actively focused on the use of non-viral vectors for gene based therapy. In May 2024, SalioGen Therapeutics inked a deal with Nanite, in order to integrate former’s Gene Coding™ technology with latter’s SAYER™ for the research and development of gene therapy to treat patients suffering from cystic fibrosis. As stated by Sean Kevlahan (Co-founder and Chief Executive Officer, Nanite), “Nanite’s relationship with SalioGen is consequential in discovering safe polymeric nanoparticles for a transformative treatment for cystic fibrosis.”
The delivery of biologics (and small molecules) with non-viral vectors has emerged as a transformative approach to treat various chronic diseases. This can be attributed to the fact that non-viral drug delivery vectors are generally safer than viral vectors, exhibiting reduced immunogenicity and cytotoxicity, which is crucial for long-term therapies. Additionally, the non-viral vectors can be engineered for specific tissue targeting, enhancing their versatility across various therapeutic areas without the complications of viral integration into the host genome.
Notably, lipid nanoparticles and polymeric vehicles are the commonly used non-viral methods for mRNA vaccine delivery. This can be attributed to the fact that they are easy to synthesize, have lower immunogenicity, and can carry a larger payload than viral vectors. Therefore, integration of non-viral drug delivery systems into clinical practice offers a promising approach to improve patient outcomes in chronic disease management.
The current technology landscape features the presence of close to 135 companies engaged in providing non-viral drug delivery systems / technologies. Interestingly, close to 50% of the technologies provided by these companies utilize encapsulation for drug interaction. It is worth mentioning that these technology providers are actively engaged in extensive research and development in order to overcome any regulatory challenges associated with non-viral drug delivery technologies.
Non-viral drug delivery technology providers have forged several strategic partnerships with other stakeholders to drive technological advancements for the development of non-viral drug delivery systems, in order to support the safe and effective delivery of biologics to the target cells. It is worth highlighting that in the last two years, more than 45% of the partnerships were inked; of which majority of the partnerships were signed for technology licensing agreement and technology integration agreement (20%, each). This can be attributed to the persistent efforts of stakeholders aimed at utilizing such technologies for the development of biologics in order to advance drug delivery technologies.
Based on the key geographical regions, the non-viral drug delivery systems market is distributed into North America, Europe and Asia-Pacific. Currently, close to 50% of the overall market is captured by North America, followed by Europe. This can be attributed to the fact that North America leverages its significant investments in advancing drug delivery technologies and a large pool of established pharmaceutical companies actively developing new delivery systems. Further, majority of the deals related to non-viral drug delivery technology occurred in North America. Therefore, it is anticipated that North America will capture majority of the market share.
However, in Asia-Pacific, the market will show significant growth potential, anticipated to grow at a higher CAGR during the forecast period. This can be attributed to the increasing support from government organizations for the development of novel non-viral drug delivery technologies, increasing healthcare infrastructure and rising partnerships between industry players.
Examples of non-viral drug delivery systems providers (which have also been profiled in this market report; the complete list of companies is available in the full report) include Arcturus Therapeutics, Bio-Path Holdings, CureVac, Entos Pharmaceuticals, etherna, Matinas Biopharma, MDimune and PCI Biotech.
The market report presents an in-depth analysis, highlighting the capabilities of various stakeholders in this industry, across different geographies. Amongst other elements, the market report includes:
Several recent developments related to non-viral drug delivery systems industry have been outlined below. These developments, even if they took place post the release of our market report, substantiate the overall non-viral drug delivery systems market trends that we have outlined in our analysis.