
Lowest Price Guaranteed
Pages
421
Last Updated
August 2026
View Count
53700
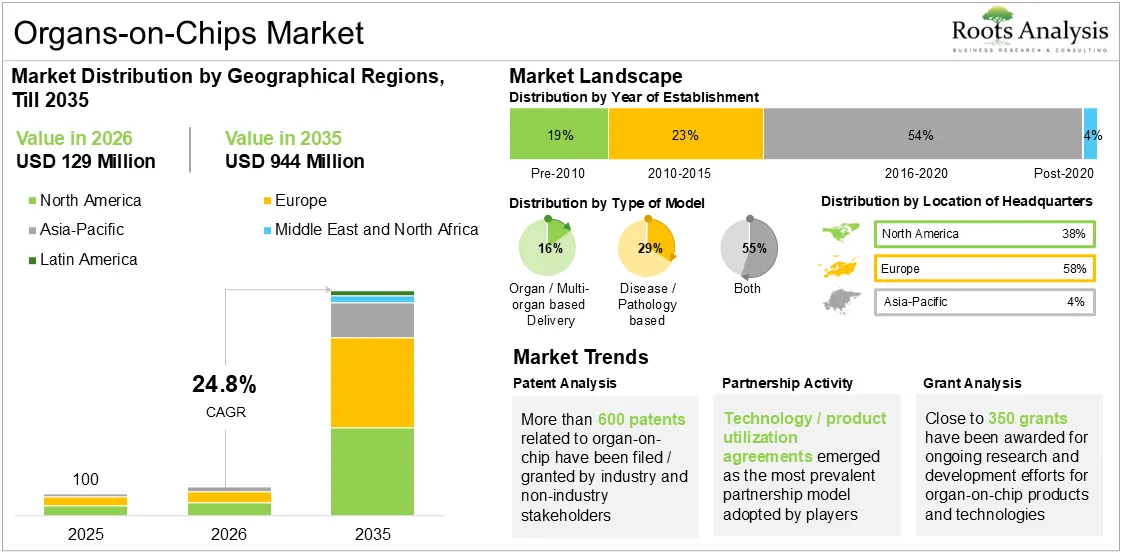
The global organs-on-chips market, valued at USD 100 million in 2025, is projected to reach USD 129 million in 2026 and USD 944 million by 2035, representing a CAGR of 24.8% during the forecast period 2026-2035.
To learn more about this report, request a free sample copy
Drug development continues to face a persistent translation gap between preclinical success and clinical performance. In the US, only a small fraction of potential drug candidates advances from preclinical testing into clinical trials. Moreover, a large proportion of those that enter human studies ultimately fail, primarily due to insufficient efficacy or unexpected toxicity. One of the key reasons for this high attrition is the limited ability of conventional animal-based models to accurately replicate human biology, disease complexity, and organ-level responses.
Organs-on-chips technology has emerged as one of the most promising solutions to address this challenge. These microfluidic systems use living human cells to recreate key structural, mechanical, and functional features of human organs in a controlled in vitro environment. By simulating tissue-tissue interactions, fluid flow, concentration gradients, and dynamic mechanical forces, organ-on-chip platforms can offer a more physiologically relevant view of how drug candidates may behave in the human body.
This technological advancement also aligns with the broader industry transition toward ethical, sustainable, and human-relevant testing approaches. Pharmaceutical manufacturers, biotechnology companies, CROs, and academic institutions are increasingly using advanced in vitro models to complement or, in selected cases, reduce dependence on animal testing. Further, this shift is reinforced by regulatory initiatives supporting New Approach Methodologies (NAMs). For instance, the US Food and Drug Administration (FDA) has increasingly incorporated NAMs into regulatory science through initiatives such as its Alternative Methods Working Group and guidance encouraging the use of scientifically validated non-animal approaches where appropriate. Similarly, the US Environmental Protection Agency (EPA) continues to promote the development and application of NAMs to modernize chemical safety assessments while reducing dependence on animal testing. Collectively, these initiatives are expected to strengthen regulatory confidence in human-relevant testing platforms, thereby expanding the role of organ-on-chip technologies in preclinical research and translational drug development.
In response to these technological and regulatory developments, organs-on-chips technology developers, microfluidics companies, and life science tool providers are investing in proprietary organ-on-chip platforms, disease-specific models, and specialized testing services to support early-stage drug discovery and preclinical evaluation. Continuous innovation in platform design, cell sourcing, and multi-organ integration is expected to further enhance the predictive capabilities and commercial adoption of these systems across pharmaceutical and biotechnology research.
| Company | YoE | Headquarters | Key Platform / Product | Market Relevance |
| AlveoliX | 2019 | Bern, Switzerland | AX Lung-on-Chip System | AlveoliX is relevant for lung-on-chip models that recreate alveolar air-blood barrier conditions and breathing-like dynamics. |
| CN Bio | 2008 | Cambridge, United Kingdom | PhysioMimix® | CN Bio is positioned around organ-on-chip models for drug discovery and development, including liver and multi-organ applications. |
| Emulate | 2014 | Massachusetts, USA | Organ-Chips including Liver-Chip and Lung-Chip | Emulate is one of the most visible commercial organ-on-chip companies, with platforms designed to run functional human biology and disease models at different throughput levels. |
| Hesperos | 2015 | Florida, USA | Human-on-a-Chip® | Hesperos focuses on human-on-a-chip models for disease modeling and drug testing, with interlinked organ systems for translational research. |
| InSphero | 2009 | Schlieren, Switzerland | Akura Organ-on-Chip Platforms | InSphero's Akura organ-on-chip platforms add physiological flow, organ-organ interaction and immune competence to 3D in vitro experiments. |
| MIMETAS | 2013 | Oegstgeest, Netherlands | OrganoPlate® Platform | MIMETAS is differentiated by its scalable OrganoPlate platform, designed to integrate with automated workflows, microscopes and plate readers. |
| NETRI | 2018 | Lyon, France | Neuro-Organ-on-Chip Kits | NETRI is a France-based organ-on-chip company focused on preclinical neuroscience applications and ready-to-use organ-on-chip kits. |
| TissUse | 2010 | Berlin, Germany | HUMIMIC Platform | TissUse is relevant for multi-organ modeling, with HUMIMIC Chip4 enabling integration of up to four organ models such as intestine, liver, kidney and neuronal tissue. |
Abbreviation: YoE: Year of Establishment
Based on the research, we have segmented the Organs-on-Chips Market into type of product, type of organ, type of single organ-based model, type of material, purpose, application area, end user, geographical regions and leading players.
By Type of Product
By Type of Organ
By Type of Single Organ-based Model
By Type of Material
By Purpose
By Application Area
By End User
By Geographical Regions
Driven by advances in microphysiological system engineering and increasing adoption of human-relevant disease models, the organs-on-chips market is entering a new expansion phase beyond single-tissue platforms.
Emphasizing this shift, Andries van der Meer (Professor, University of Twente), stated, "Organ-on-Chip technology offers a solution by mimicking the complexity of the human body in a controlled laboratory environment. This makes it possible to study human responses more accurately. The technology is cost- and time-efficient and can be optimized for future generations of models."
Discussions with multiple stakeholders in this domain have influenced the opinions and insights presented in this study. The market report includes transcripts of the following discussions:
In addition, the market report includes transcripts of the following third-party discussions:
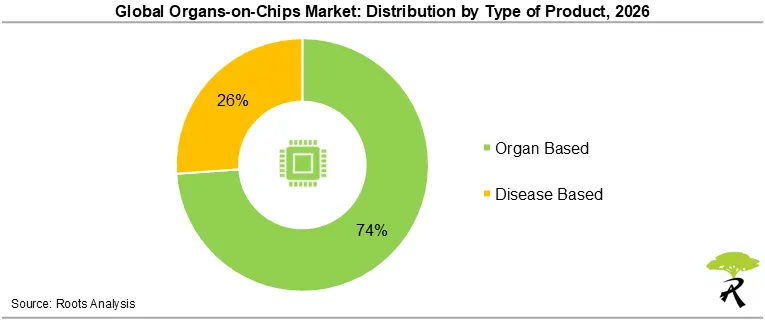
Based on the type of product, the global organs-on-chips market is segmented into Organ-based and Disease-based.
Currently, organ-based models account for the largest share of the overall organ-on-chips market, capturing ~75% share. This is because of their extensive use in drug discovery, toxicity testing, disease modeling, and preclinical research. These models accurately replicate the structural architecture, physiological functions, and microenvironment of individual human organs, enabling researchers to generate more predictive human-relevant data than conventional in vitro cell culture and animal models.
Furthermore, regulatory agencies and pharmaceutical companies are increasingly adopting organ-specific microphysiological systems to improve preclinical decision-making and reduce late-stage drug attrition. For example, Emulate has commercialized liver-, lung-, intestine-, and kidney-on-chip platforms that are widely used by pharmaceutical companies for safety assessment and drug development. Additionally, MIMETAS also offers organ-specific tissue models for preclinical screening. The maturity of these platforms, combined with their broad applicability across multiple therapeutic areas have reinforced the dominance of the organ-based models.
The disease-based models segment is likely to grow at a significant pace during the forecast period due to the pharmaceutical industry's increasing emphasis on disease-specific drug discovery and precision medicine. Drug developers are shifting from evaluating compounds in healthy tissue models to disease-relevant microphysiological systems that better replicate pathological conditions such as cancer, metabolic disorders, neurodegenerative diseases, fibrosis, and inflammatory diseases.
Based on the type of organ, the global organs-on-chips market is segmented into single organ-based and multi organ-based.
Currently, single organ-based models account for the largest share of the global organ-on-chips market. This dominance is primarily due to their higher level of technological maturity, broader commercial availability, and widespread adoption in pharmaceutical preclinical workflows. Most drug candidates undergo organ-specific evaluations, particularly for liver metabolism, cardiotoxicity, nephrotoxicity, pulmonary toxicity, and intestinal absorption, before advancing to clinical development. As a result, pharmaceutical and biotechnology companies routinely invest in validated single-organ platforms that can be easily incorporated into existing ADME toxicology testing, and efficacy and safety testing pipelines.
Moreover, regulatory agencies and industry consortia have generated substantially more validation data for single-organ systems than for interconnected multi-organ platforms, increasing industry confidence in their use. For example, AlveoliX, BiomimX and React4Life provide commercially available organ-specific platforms spanning lungs, heart, gut, liver, skin, and joint models for drug efficacy, metabolism, safety and toxicity studies. Their focused biological scope, standardized experimental workflows, and comparatively lower implementation complexity have supported the continued dominance of the single-organ models segment.
The multi-organ models segment is likely to grow at a significant pace during the forecast period owing to the increasing demand for physiologically integrated human models capable of predicting whole-body drug responses. Notably, multi-organ platforms enable researchers to study how drugs are metabolized in one organ and subsequently affect others, providing insights that cannot be obtained using isolated organ models. Furthermore, growing collaborations between pharmaceutical companies, regulatory agencies, and organ-on-chip developers to reduce animal testing and improve prediction of human clinical outcomes are expected to drive robust growth of the multi-organ models segment during the forecast period.
Based on purpose, the organs-on-chips market is segmented into research purposes and therapeutic purposes.
Research purposes hold the largest share of the organs-on-chips market owing to the extensive adoption of organ-on-chip platforms during the early stages of drug discovery, target identification, disease mechanism studies, and preclinical safety assessment. Pharmaceutical and biotechnology companies, academic research institutions, and contract research organizations (CROs) increasingly utilize these platforms to generate human-relevant data before progressing drug candidates to animal studies or clinical trials, thereby improving decision-making and reducing late-stage attrition. Moreover, substantial public and private funding for biomedical research, coupled with growing collaborations between industry and academia, has accelerated the adoption of organ-on-chip technologies for fundamental and translational research.
For example, Emulate has partnered with leading pharmaceutical companies and research institutions to integrate organ-on-chip platforms into drug discovery and toxicology studies, while initiatives supported by organizations such as the National Institutes of Health have further expanded their use in biomedical research. The large volume of research activities compared to commercial therapeutic applications has reinforced the dominance of the research purposes segment.
The therapeutic purpose segment is likely to grow at a significant pace during the forecast period owing to the increasing integration of organ-on-chip technologies into precision medicine and patient-specific therapeutic development. Pharmaceutical companies are increasingly employing patient-derived organ-on-chip models to predict drug efficacy, optimize dosing strategies, and evaluate personalized treatment responses before clinical administration. Additionally, growing investments in cell and gene therapies, biologics, immunotherapies, and regenerative medicine are driving demand for physiologically relevant platforms that can better predict therapeutic outcomes than conventional preclinical models.
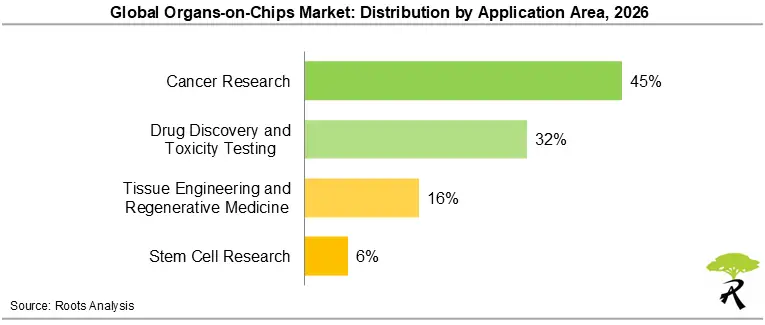
Based on application area, the global organs-on-chips market is segmented into drug discovery / toxicity testing, cancer research, stem cell research and tissue engineering / regenerative medicine.
Currently, cancer research holds the largest share of the organs-on-chips market owing to the substantial global investment in oncology drug development and the high attrition rates associated with cancer therapeutics during clinical trials. Oncology accounts for the largest proportion of pharmaceutical R&D pipelines, prompting drug developers to increasingly adopt organ-on-chip platforms to improve the predictive accuracy of preclinical efficacy and toxicity studies before advancing candidates into costly cancer-related clinical trials. Moreover, the rapid expansion of immuno-oncology, antibody-drug conjugates (ADCs), cell and gene therapies, and targeted therapies have increased the demand for physiologically relevant tumor models capable of evaluating complex tumor biology and therapeutic responses.
Further, the cancer research segment is likely to grow at a significant pace during the forecast period owing to the increasing complexity of next-generation oncology therapeutics pipeline and the growing need for human-relevant preclinical models to accelerate drug development.
In terms of geographical regions, the global organs-on-chips market is segmented into North America, Europe, Asia-Pacific, Middle East and North Africa, and Latin America.
Currently, North America accounts for the largest share of the organ-on-chips market. This dominance is due to its well-established biopharmaceutical industry, substantial investment in biomedical research, and early adoption of advanced preclinical technologies.
Moreover, the region is home to several leading organ-on-chip developers, including Emulate, CN Bio (U.S. operations), and numerous biotechnology startups that collaborate extensively with global pharmaceutical companies to accelerate drug discovery and toxicology studies. Major pharmaceutical companies such as Pfizer, Merck & Co., and Johnson & Johnson have also increasingly incorporated organ-on-chip platforms into preclinical R&D to improve the prediction of human drug responses and reduce late-stage clinical failures.
The Europe organs-on-chips market is likely to grow at a significant pace during the forecast period owing to increasing regulatory support for alternatives to animal testing, expanding public funding for advanced in vitro technologies, and growing collaborations between academia, biotechnology companies, and pharmaceutical manufacturers.
The region has witnessed strong momentum following the European Union's continued commitment to reducing animal experimentation and promoting New Approach Methodologies, encouraging greater adoption of organ-on-chip platforms in drug development and safety assessment. In addition, Europe is home to leading organ-on-chip innovators such as MIMETAS, TissUse, and InSphero, which continue to expand partnerships with pharmaceutical companies and research institutions.
| Key Report Attribute | Details | |
| Historical Trend | Since 2019 | |
| Forecast Period | Till 2035 | |
| Market Size 2026 | USD 129 Million | |
| Market Size 2035 | USD 944 Million | |
| CAGR (Till 2035) | 24.8% | |
| Segments Covered |
|
|
| Key Players | (A complete list of players captured is available in the report) | |
| PowerPoint Presentation (Complimentary) |
Available | |
| Customization Scope | 15% Free Customization | |
| Excel Data Packs (Complimentary) |
Available | |