Peptide Synthesis Market 3rd Edition, 2026 to 2035
Peptide Synthesis Market by Type of API (Generic APIs and New Chemical Entities), Type of Peptide Synthesis Method (Chemical Synthesis and Non-Chemical Synthesis), Type of Chemical Synthesis Method (Solid Phase Synthesis, Liquid Phase Synthesis, and Hybrid Phase Synthesis), Scale of Operation (Commercial Scale and Preclinical / Clinical Scale), Company Size (Small Companies, Mid-sized Companies, and Large and Very Large Companies), Geographical Regions- Trends and Forecast 2026-2035
-
Lowest Price Guaranteed
-
Pages
390 -
Last Updated
October 2026 -
View Count
39138 -
Peptide Synthesis Market Size USD 4.4 Billion in 2026
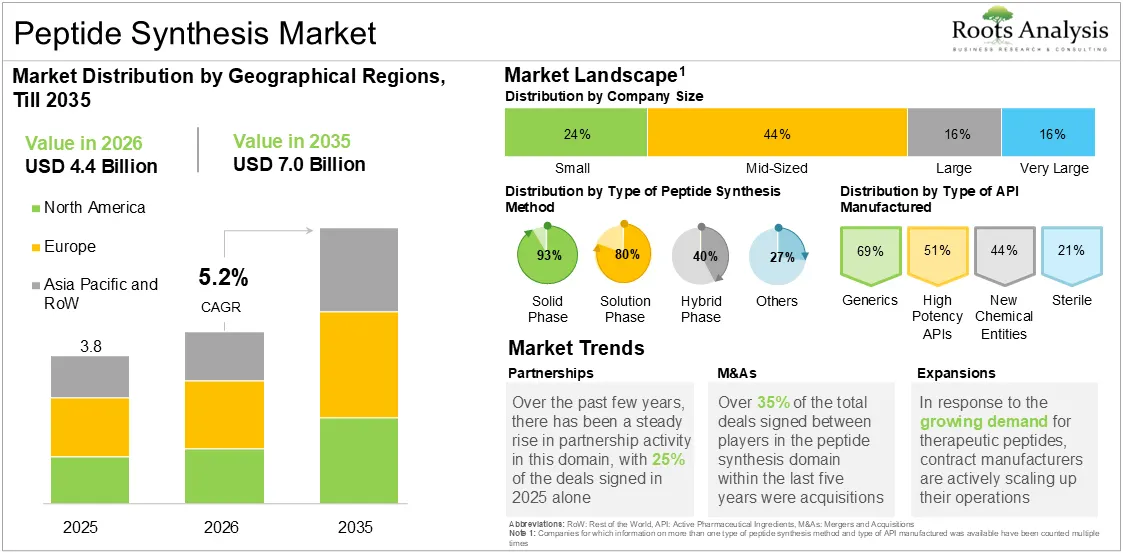
The global peptide synthesis market, valued at USD 3.8 billion in 2025, is projected to reach USD 4.4 billion in 2026 and USD 7.0 billion by 2035, at a CAGR of 5.2% during the forecast period 2026 to 2035. This market size refers to the peptide API contract manufacturing opportunity rather than the broader market for peptide synthesizers, reagents, consumables or research-only peptide products. The market growth is being supported by the expanding pipeline of peptide therapeutics, rising commercial demand for metabolic and other chronic-disease therapies, and continued outsourcing of specialized peptide API manufacturing.
To learn more about this report, request a free sample copy
Market Report: Key Takeaways
- Generic peptide APIs currently account for the highest share of the market revenues, supported by established commercial products and increasing generic opportunities.
- Chemical synthesis accounts for the largest share of the market and remains the primary route for manufacturing many therapeutic peptides.
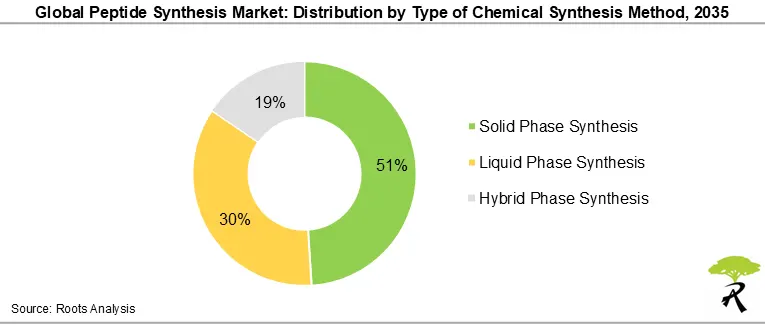
- Solid phase peptide synthesis (SPPS) holds majority (more than 50%) of the chemical synthesis segment, while hybrid synthesis is projected to grow at a higher CAGR during the forecast period.
- Commercial-scale manufacturing accounts for the largest share of the current market revenues because long-term GMP supply contracts generate substantially more value than smaller preclinical and clinical batches.
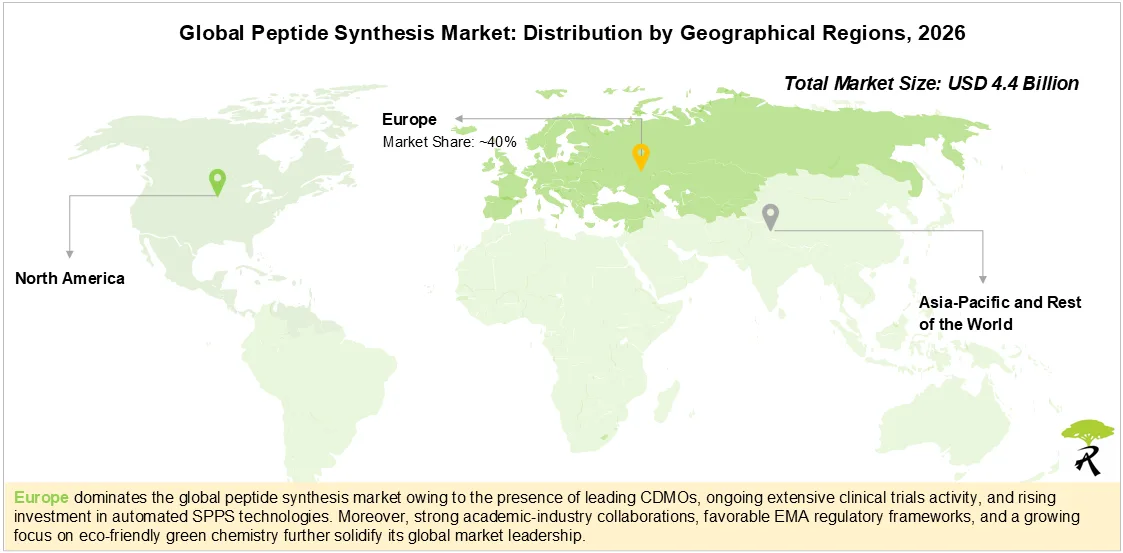
- Europe currently holds approximately 40% of the market, while Asia-Pacific is expected to register the fastest growth as regional manufacturing capabilities expand.
Key Market Statistics
- Market size, 2026: USD 4.4 Billion
- Market size, 2035: USD 7.0 Billion
- CAGR, 2026-2035: 5.2%
- Largest API segment: Generic APIs
- Largest region: North America
What is Peptide Synthesis Market?
Peptides are short chains of amino acids linked through peptide bonds. In pharmaceutical development, synthetic peptides are used as active ingredients in therapies across metabolic, oncological, endocrine and other disease areas. Custom peptides are also used in research, vaccine development and diagnostic assays; however, the market sizing in this report is focused specifically on outsourced peptide API development and manufacturing.
Contract manufacturers support pharmaceutical and biotechnology companies from early development through clinical and commercial supply. Services can include route selection, process development, peptide synthesis, modification, purification, analytical testing, scale-up, GMP manufacturing, lyophilization and regulatory support. Outsourcing is particularly important when sponsors do not have sufficient internal manufacturing infrastructure, specialized chemistry expertise or capacity to support complex peptide programs.
What is Driving Peptide Synthesis Market Growth?
The strongest demand is coming from the expansion of peptide therapeutics for chronic diseases, particularly obesity and diabetes, as well as oncology and other specialty indications. GLP-1 and dual-agonist programs have materially increased the need for large-scale peptide active ingredient manufacturing, while a broader clinical pipeline continues to create demand for flexible preclinical, clinical and commercial capacity.
Methodology and Industry Expert Interviews
The report is supported by a structured research methodology that combines secondary research, proprietary databases and primary stakeholder discussions. The underlying study includes demand analysis, capacity analysis, regional capability assessment, company competitiveness, likely-partner analysis, make-versus-buy assessment, total cost of ownership and market forecasting.
The report includes detailed interviews with seven industry stakeholders representing executive, scientific, financial, commercial and peptide-manufacturing roles across organizations in Germany, the US, Ireland, Japan and India. These discussions informed the assessment of capacity constraints, outsourcing behavior, manufacturing complexity, technology adoption and future demand.
- Founder and Owner, Small Company, Germany
- Chief Financial Officer, Small Company, Germany
- Chief Business Officer, Small Company, US
- Senior Director of Scientific Affairs and Technical Marketing, Small Company, US
- Vice President, Peptides, Large Company, Ireland
- Senior Manager, Peptide Business Project Leader, Large Company, Japan
- Chief Scientific Officer, Co-Founder, Small Company, India
In May 2025, following the announcement of a significant investment of over €900 million into its peptide manufacturing capabilities, CordenPharma CEO & President, Dr. Michael Quirmbach, stated: "The peptide space is currently experiencing an explosion in demand, primarily driven by innovative molecules aimed at treating diabetes and obesity. These peptides are complex to manufacture, and there is a clear shortage of manufacturing capacity globally".
Recent Developments in the Peptide Synthesis Domain
- In August 2026, CordenPharma completed the acquisition of AmbioPharm, adding peptide API manufacturing operations in South Carolina and Shanghai and expanding its global peptide development, purification and commercial manufacturing network.
- In July 2026, Bachem announced plans to invest more than CHF 500 million in a large-scale peptide production facility in Sisslerfeld, Switzerland, under a strategic long-term supply collaboration. Commercial production is expected to begin in 2030.
- In March 2026, PolyPeptide reported that newly added SPPS capacity at its Strasbourg, France site had become operational and was expected to ramp up production throughout 2026, alongside additional capacity investments across its global network.
How is Peptide Synthesis Market Segmented?
The report evaluates the market by type of API, type of peptide synthesis method, type of chemical synthesis method, scale of operation, company size and geography. This report segmentation structure supports pharmaceutical and biotechnology companies, business-development teams, R&D and process-development groups, procurement and purchasing functions, quality and regulatory teams, supply-chain leaders, investors and other stakeholders assessing peptide manufacturing capacity and outsourcing partners.
- By Type of API: Generic APIs and New Chemical Entities
- By Type of Peptide Synthesis Method: Chemical Synthesis and Non-Chemical Synthesis
- By Type of Chemical Synthesis Method: Solid Phase Synthesis, Liquid Phase Synthesis, and Hybrid Phase Synthesis
- By Scale of Operation: Commercial Scale and Preclinical / Clinical Scale
- By Company Size: Small Companies, Mid-sized Companies, and Large and Very Large Companies
- By Geographical Regions: North America (US and Canada), Europe (Belgium, Switzerland, UK, Germany, Ireland, Netherlands, Italy, France, Sweden, and Rest of Europe), Asia-Pacific and Rest of the World (China, India, Japan, Korea, and Other Countries)
Peptide Synthesis Market Share Insights
Which API Segment Leads the Market?
Generic APIs currently account for approximately 88% of market revenues. Their position reflects the commercial maturity of several first-generation peptide products, patent expirations and the cost pressure associated with branded therapies. New chemical entities represent a smaller share but remain important to future pipeline growth.
Which Peptide Synthesis Method Holds the Largest Share?
Chemical synthesis currently accounts for approximately 85% of the market, supported by its broad applicability, scalability and established use in commercial peptide API manufacturing.
Which Chemical Synthesis Method Leads the Global Peptide Synthesis Market?
Solid phase peptide synthesis currently accounts for approximately 50% of the chemical synthesis segment. Hybrid synthesis is projected to grow faster, at a CAGR of approximately 7.2%, because it can combine the strengths of solid- and liquid-phase approaches for complex and longer peptide sequences.
Which Scale of Operation Generates the Most Revenue?
Commercial-scale manufacturing currently accounts for more than 90% of market revenues. Large commercial batches and long-term GMP supply agreements generate substantially more revenue than smaller preclinical and clinical projects.
How Are Peptide Synthesis Technologies Evolving?
Solid phase peptide synthesis remains a core manufacturing technology. SPPS builds the peptide chain through stepwise coupling of protected amino acids on a solid resin, followed by cleavage of the completed peptide from the resin, enabling rapid cycle-based synthesis and simplified separation of excess reagents. Liquid phase peptide synthesis can be suitable for selected sequences and larger-scale processing, while hybrid approaches combine SPPS and LPPS to improve efficiency for longer or more complex peptides.
Emerging technologies are expanding the manufacturing toolkit. Chemo-enzymatic synthesis, continuous-flow processing, advanced process control, laboratory automation and modular manufacturing systems are being evaluated to improve productivity, reproducibility and scale-up. Artificial intelligence and machine-learning tools are also emerging in peptide discovery and process optimization, but their manufacturing use should be viewed as an enabling technology rather than a standalone market segment.
Sustainability is becoming increasingly important because conventional peptide synthesis can consume significant quantities of solvents, reagents and single-use materials. Green chemistry initiatives are therefore focused on solvent substitution, solvent recycling, process intensification, improved coupling efficiency and waste reduction without compromising peptide quality or regulatory compliance.
Regional and Manufacturing Capability Analysis: Peptide Synthesis Market
Europe
Europe currently accounts for approximately 40% of the global peptide synthesis market, supported by established peptide manufacturers, significant installed capacity, a strong research ecosystem and extensive academic-industry collaboration. Belgium and Switzerland are important European manufacturing and biotechnology hubs, while additional capabilities are distributed across Germany, Ireland, the Netherlands, Italy, France, Sweden and the UK.
Asia-Pacific
Asia-Pacific is expected to register the fastest growth as regional pharmaceutical manufacturing expands and companies invest in peptide API capabilities. China, India, Japan and Korea are increasingly important to the regional supply base, supported by lower operating costs in selected markets, growing technical expertise and investment in new facilities.
North America
North America remains a major peptide development and manufacturing market because of its large pharmaceutical and biotechnology ecosystem, clinical pipeline and growing emphasis on domestic supply resilience. Recent investments in US peptide API capacity illustrate the importance of manufacturing-location strategy in long-term supply planning.
Peptide Synthesis Market: Key Insights
Purification, Analytical Control and Quality Assurance Are Critical to Peptide API Manufacturing
Peptide synthesis does not end when the sequence is assembled. Crude material can contain deletion sequences, truncated peptides, stereochemical impurities, residual reagents and other process-related impurities that must be controlled before release. High-performance liquid chromatography (HPLC) and other chromatographic methods are widely used for purification and analytical assessment, often supported by mass spectrometry and complementary techniques for identity, purity and impurity characterization.
Quality requirements become more stringent as a program moves from research to clinical and commercial manufacturing. GMP peptide API production requires qualified equipment, validated or appropriately controlled processes and analytical methods, robust documentation, change control, deviation management, data integrity, stability programs and defined release specifications. Verification and validation activities therefore form an important part of technology transfer and commercial scale-up.
Regulatory Compliance Is Becoming More Peptide-Specific
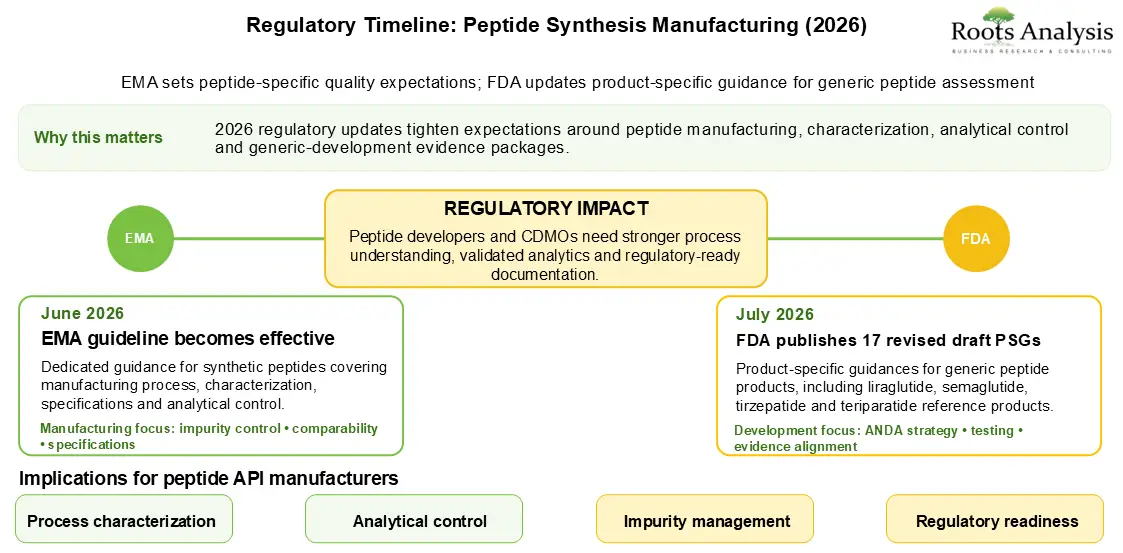
Peptide manufacturers must comply with applicable GMP requirements for active pharmaceutical ingredients and maintain quality systems that support regulatory submissions in major markets. In Europe, the EMA guideline on the development and manufacture of synthetic peptides became effective on 1 June 2026 and addresses manufacturing processes, characterization, specifications and analytical control for synthetic peptides. In the US, FDA cGMP requirements and ICH Q7 principles remain important foundations for API manufacturing quality.
Regulatory expectations are also evolving for generic peptide products. In July 2026, the FDA published revised draft product-specific guidance for 17 peptide products, including semaglutide, liraglutide and teriparatide. For contract manufacturers, these developments reinforce the need for strong impurity characterization, process understanding, analytical precision and regulatory-ready documentation.
When Does Outsourcing Peptide Manufacturing Create the Most Value?
The make-versus-buy decision depends on development stage, expected demand, sequence complexity, purity requirements, manufacturing route, internal capacity and the cost of building or expanding dedicated peptide infrastructure. In-house manufacturing can provide direct control over scheduling and proprietary processes, but it also requires capital investment in synthesis, purification, lyophilization, analytical laboratories, utilities, validation and trained personnel.
Outsourcing can provide faster access to specialized capacity and reduce fixed capital exposure, particularly for sponsors moving from milligram- or gram-scale development into multi-kilogram clinical or commercial supply. The total cost of ownership should therefore consider not only manufacturing price, but also capacity utilization, technology transfer, analytical development, quality oversight, supply-chain risk, project management and time to market.
What Should Sponsors Evaluate in a Peptide Manufacturing Partner?
Partner selection should begin with technical fit. Sponsors should assess experience with the intended synthesis route, peptide length and complexity, required modifications, target purity, scale and downstream purification requirements. High-performance liquid chromatography capability, analytical depth, lyophilization capacity, GMP history, regulatory inspection experience and the ability to transfer a process from development to commercial scale are particularly important.
Commercial and operational factors are also relevant. Procurement and business-development teams may evaluate available capacity, supply-chain resilience, project governance, technical support, turnaround time, geographic redundancy, confidentiality, intellectual property protection, data security and cost. The strongest outsourcing relationships typically combine manufacturing capability with transparent project management and long-term capacity planning.
Who are the Key Players in Peptide Synthesis Market?
The report profiles Amneal Pharmaceuticals, Asymchem, Aurisco Pharma, Dr Reddy's Laboratories, Hybio Pharmaceutical, JYMed Peptide, Neuland Labs, Sinopep-Allsino Biopharmaceutical, SK Pharmteco, and WuXi STA (a WuXi AppTec company). This market report includes an easily searchable excel database of all the companies that are engaged in cytotoxic drugs and HPAPI manufacturing industry.
Report Deliverables and Customization
The report includes complimentary Excel data packs covering market landscape analysis, company competitiveness, recent developments, clinical trials, demand analysis, capacity analysis, likely partner analysis, total cost of ownership and market sizing and forecast analysis. A complimentary PowerPoint presentation is available, and up to 15% customization can be requested subject to data availability.
Report Authorship
This report has been co-authored by Simriti Gupta and Pemba Lahmo, both part of Roots Analysis's healthcare and pharma research practice. Their work focuses on competitive intelligence, company benchmarking and market forecasting.
Independence and Non-Affiliation
Roots Analysis is an independent market research and consulting firm. This report is not affiliated with, endorsed by, sponsored by or produced on behalf of any pharmaceutical company, biotechnology company, CDMO, equipment supplier or individual named or quoted in the study. Company names, facility information, product references and expert commentary are included solely for factual, market-analysis and competitive-intelligence purposes.