Allogeneic Cell Therapy Market by Type of Cell Therapy (Mesenchymal Stem Cell Therapies, Progenitor Stem Cell Therapies, Embryonic Stem Cell Therapies, T-cell Therapies, Fibroblast Cell Therapies, Retinal Cell Therapies, Pancreatic Islet Cellular Therapies, Tissue-based Regenerative Therapies and Hematopoietic Stem Cell Therapies), Route of Administration, Target Indication, Therapeutic Area and Geographical Regions -Trends and Forecast, 2026-2035
A $6,013 Million Opportunity by 2035
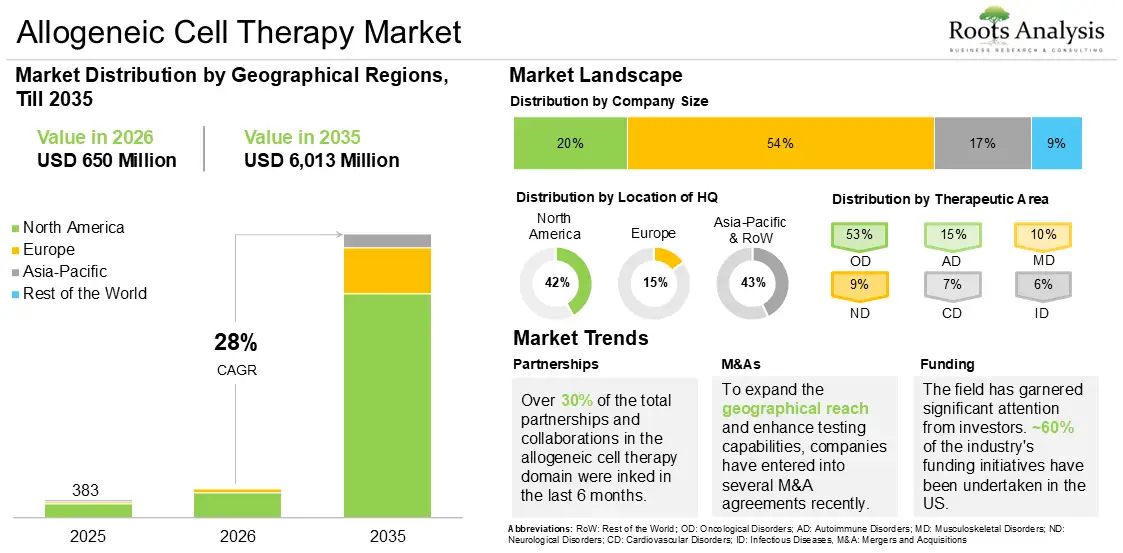
The allogeneic cell therapy market, valued at USD 383 million in 2025, is projected to reach USD 650 million in 2026 and USD 6,013 million by 2035, representing a CAGR of 28% during the forecast period 2026 to 2035. Growth is being supported by expanding clinical pipelines, the potential for off-the-shelf availability, scalable batch manufacturing from qualified donor-derived cells and cell banks, advances in cell engineering, and increasing investment in automated manufacturing and commercialization infrastructure.
See What's in the Full Report – Request Your Complimentary Insights!
Key Takeaways
Market Size & Trends
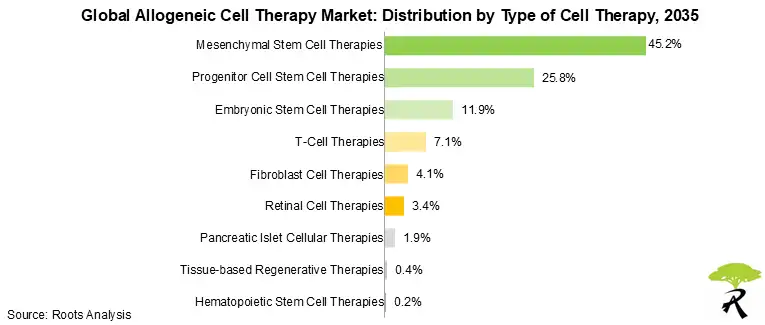
- The mesenchymal stem cell therapy is projected to dominate the market, supported by broad clinical development activity, immunomodulatory properties, established donor sourcing and potential for scalable expansion and batch production.
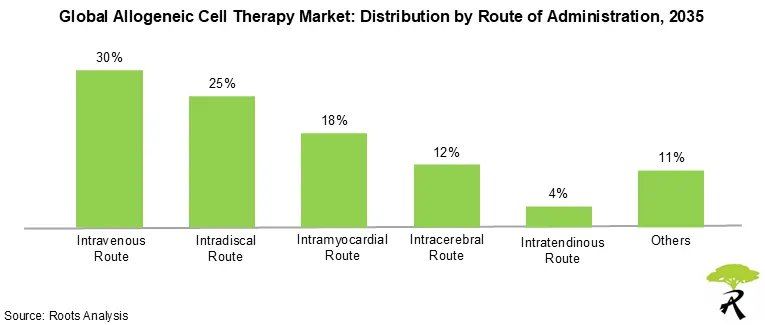
- By route of administration, the intravenous route is expected to account for around 30% of market revenue, reflecting its established use for systemic delivery of therapeutic cells directly into the bloodstream.
- By target indications, heart failure is expected to represent a leading opportunity, supported by the global burden of chronic cardiovascular diseases, persistent unmet need in advanced heart failure and ongoing clinical development of regenerative cell-based approaches.
- By therapeutic area, cardiovascular disorder accounts for the highest share of the market, reflecting the substantial patient burden associated with heart failure and other cardiovascular conditions, together with continued clinical evaluation of cell-based therapies for tissue repair and functional recovery.
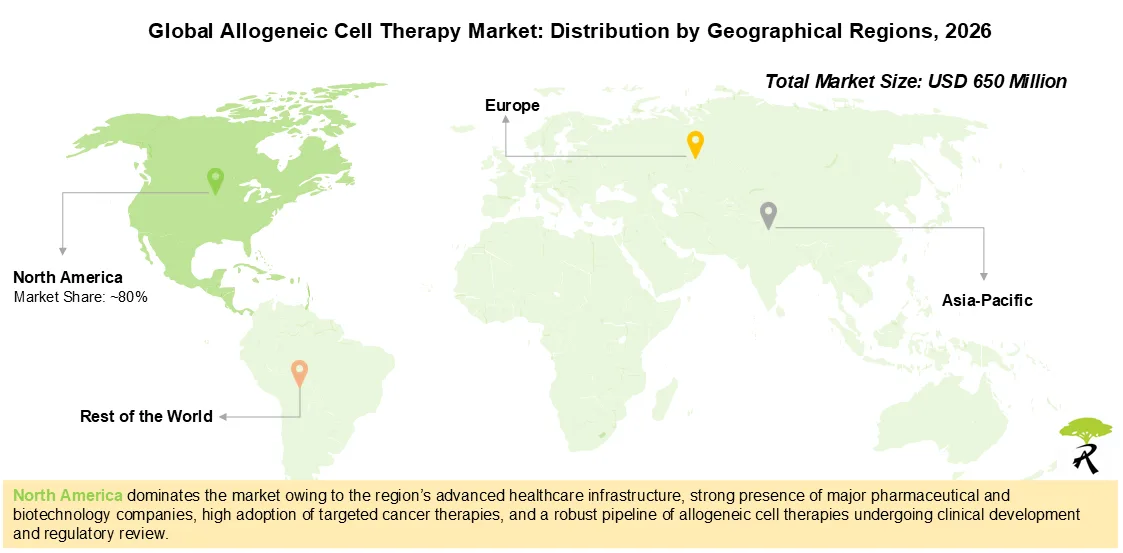
- By geography, North America is projected to capture the largest share (~80%) of the allogeneic cell therapy market, supported by an established biotechnology ecosystem, advanced healthcare and clinical-trial infrastructure, regulatory experience and sustained investment in cell therapy manufacturing and development.
Key Market Statistics
- Market Size in 2026: $650 Million
- Estimated Market Size in 2035: $6,013 Million
- CAGR (2026-2035): 28%
- North America: Largest Market in 2026
- Europe: Fastest Growing Region
Scope, Methodology and Industry Expert Interviews
This report has been prepared by the Roots Analysis biopharmaceutical research team. The report supports biopharmaceutical companies, business and commercial development leaders, procurement and sourcing teams, and investors as they compare allogeneic cell therapy capabilities, assess manufacturing risk, evaluate capacity, and identify partnership opportunities.
Built on Interviews With 14 Named Industry Stakeholders
This study includes transcripts of 14 structured stakeholder interviews with chief medical officers, chief scientific officer, vice president, co-founder & chief technical officers, chief commercial officer and director from large, mid-sized, and small allogeneic cell therapy focused organizations across Europe, North America, and Asia.
Discussions with multiple stakeholders in this domain influenced the opinions and insights presented in this study. The market report includes transcripts of the following discussions:
- Chief Executive Officer, Small Company, Netherlands
- Chief Medical Officer, Mid-sized Company, Australia
- Chief Scientific Officer, Small Company, US
- Vice President, Small Company, Belgium
In addition, the market report includes transcripts of the following other third-party discussions:
- Director of Genome Engineering, Small Company, Belgium
- Co-Founder & Chief Technical Officer, Mid-sized Company, Belgium
- Chief Commercial Officer, Mid-sized Company, Belgium
- Senior Vice President, Cell Therapy Research, Mid-sized Company, Belgium
- Director of Cell Therapy Innovation, Mid-sized Company, Belgium
- Chief Technology & Manufacturing Officer, Mid-sized Company, US
- Marketing Manager, Mid-sized Company, Japan
- Former Chief Patient Supply Officer, Mid-sized Company, US
- President & Chief Executive Officer, Mid-sized Company, US
- Former President & Chief Executive Officer, Mid-sized Company, Israel
Andreas Bader (Chief Scientific Officer at Triumvira Immunologics), stated that, "There is a significant demand for allogeneic cell therapies in the US and Asian markets. Both markets have always been and will continue to remain on the forefront in terms of technological advancements related to this field. Europe is also expected to capture a substantial share of the allogeneic cell therapies market. Further, I believe that the ongoing improvements in technologies will increase the adoption of allogeneic cell therapies on these continents."
What are Allogeneic Cell Therapies, and Why Do They Matter to Biotech and Pharma?
Allogeneic cell therapies use donor-derived cells and may offer off-the-shelf availability; however, developers must manage alloreactivity, host immune rejection and, where relevant, graft-versus-host disease. By integrating genetic engineering technologies like CRISPR-Cas9 and TALEN, these allogeneic cell therapies enhance the treatment of various chronic diseases, enabling pharmaceutical companies to develop more effective and targeted oncological, cardiovascular and hematological treatments.
The allogeneic cell therapy market continues to expand rapidly by leveraging innovations in infrastructure for bioreactors, shifting towards automated closed systems and the use of induced pluripotent stem cell (iPSC) master cell banks as the source of cells. However, the field still encounters challenges in reducing chances of host rejection, donor variability and cell damage during the manufacturing process, along with meeting stringent regulatory and quality standards for clinical deployment.
Achieving cost efficiency and establishing uniform characterization methodologies remain significant hurdles for widespread adoption. However, expanding applications in solid tumors and hematologic cancers, coupled with the growing investments in precision oncology, are fueling market growth.
How is Allogenic Cell Therapy Market Segmented?
The report segments the allogeneic cell therapy market by type of cell therapy, route of administration, target indication, therapeutic area and geographical regions.
- By Type of Cell Therapy: Mesenchymal Stem Cell Therapy, Progenitor Cell Stem Cell Therapy, Embryonic Stem Cell Therapy, T-cell Therapy, Fibroblast Cell Therapy, Retinal Cell Therapy, Pancreatic Islet Cellular Therapy, Tissue-based Regenerative Therapy, and Hematopoietic Stem Cell Therapy
- By Route of Administration: Intravenous, Intradiscal, Intramyocardial, Intracerebral, Intratendinous, Topical, Intraocular, Intravascular Route, Surgical Implant and Intrastriatal.
- By Target Indication: Heart Failure, Degenerative Disc Disease, Chronic Low Back Pain, Duchenne Muscular Dystrophy (DMD) , Mesial Temporal Lobe Epilepsy With Hippocampal Sclerosis, Pediatric Congenital Athymia, Leukemia, Partial Thickness Rotator Cuff Tear, Macular Telangiectasia Type 2 (MacTel), Acute Chronic Wounds, EBV-PTLD following Allogeneic Hematopoietic Cell, Transplant and Solid Organ Transplant , Type I Diabetes, Venous Leg Ulcer, Musculoskeletal Defects, Parkinson's Disease, Acute Graft-versus-Host Disease (aGVHD), Knee Osteoarthritis and Hematological Disorder
- By Therapeutic Area: Cardiovascular, Musculoskeletal, Neurological, Degenerative, Genetic, Immune, Oncological, Ophthalmic, Metabolic, Dermatological, Autoimmune, Hematological, and Other Disorders
- By Geographical Region: North America, Europe, Asia-Pacific, and Rest of the World
Allogeneic Cell Therapy Market: Key Insights
What is Driving Growth in the Allogeneic Cell Therapy Market?
Growth in the allogeneic cell therapy market is being driven by expanding clinical pipelines across oncology, cardiovascular disease, autoimmune conditions and regenerative medicine, together with demand for treatment models that can serve more patients without individualized manufacturing. Off-the-shelf inventory, scalable batch production, the ability to derive multiple doses from qualified donor material and advances in cell engineering can improve manufacturing efficiency and shorten treatment preparation timelines. Rising investments, partnerships and capacity expansions are also supporting the transition of allogeneic platforms from early clinical development toward broader commercialization.
What are the Main Challenges Limiting the Allogenic Cell Therapy Market Growth?
The primary challenges include immune rejection, graft-versus-host disease, donor variability and the difficulty of maintaining consistent cell identity, purity, potency and viability during expansion and storage. Complex genetic engineering, cell characterization and quality-control requirements can increase development risk, while cryopreservation and transport must preserve product integrity through distribution. High capital requirements, evolving regulatory expectations, long-term safety monitoring and the need to demonstrate durable clinical benefit can also delay development and commercialization of allogeneic cell therapies.
How Do Manufacturing Scale, Quality and Regulatory Requirements Shape Commercialization?
Commercial-scale allogeneic manufacturing depends on qualified donor sourcing or master cell banks, controlled cell expansion, closed-system processing and validated batch-production workflows. Automation can reduce manual variability, while in-process controls and release testing are used to evaluate attributes such as identity, purity, potency, viability, sterility and consistency across lots. These capabilities are especially important when a single manufacturing batch is intended to supply doses for multiple patients.
Regulatory compliance is critical aspect, developers must align donor qualification, Good Manufacturing Practice (GMP), process validation, comparability, change control and product-release strategies with the requirements applicable to their development stage and jurisdiction. In the US, cell therapy programs may require FDA engagement through IND and ultimately BLA pathways; European programs may require CTA and marketing-authorization planning. Safety monitoring remains central, particularly for engineered immune-cell therapies where immune rejection, graft-versus-host disease and cytokine-mediated toxicities may affect clinical development.
How Do Off-the-Shelf Logistics, Cost Efficiency and Market Access Affect Adoption?
The off-the-shelf model can reduce dependence on patient-specific manufacturing, but it does not remove supply-chain complexity. Commercial programs require coordinated inventory planning, cryogenic storage, validated shipping, batch and donor traceability, treatment-center readiness and reliable data capture across the donor-to-patient workflow. Digital tracking and manufacturing data can support chain-of-custody, quality investigations and inventory management across regions.
From a commercial perspective, scalable batch manufacturing may improve per-dose economics relative to bespoke autologous cell therapy production, but broader adoption will still depend on clinical efficacy, durability, safety, reimbursement, healthcare-system capacity and payer assessment of value. Market-access strategy therefore becomes increasingly important as allogeneic therapies progress from small clinical populations toward larger oncology, autoimmune and regenerative-medicine indications.
Recent Developments in Allogeneic Cell Therapy Market
- ENCell and Ingenium Therapeutics: In June 2026, the companies collaborated with an aim to manufacture clinical trial materials in the US for the development of Ingenium's NK cell therapy candidate, gengleucel.
- TScan Therapeutics and Cellares: In June 2026, the companies announced an agreement to evaluate automated manufacturing of TSC-101, which is the lead candidate of TScan's TCR-T therapy pipeline.
- UnicoCell Biomed and Gene & Stem Biomedical Company: In June 2026, the companies signed a joint marketing agreement to promote the development of stem cell and its related products in the Vietnamese and Southeast Asian markets.
Your Business is Unique – Why Shouldn't Your Report Be?
Market Share Insights
Mesenchymal Stem Cell Therapy is Projected to Account for the Largest Share
- By 2035, mesenchymal stem cell therapy sub-segment captures majority share of the allogeneic cell therapy market. This is because they exhibit low immunogenicity, which allows the patients to use the therapies without strict donor matching. Additionally, they are also easy to manufacture at large scale, enabling easier availability. This trend is likely to remain unchanged in the coming years as well.
- The progenitor cell stem cell therapy sub-segment is anticipated to capture the second largest share of the allogeneic cell therapy market by 2035, owing to its broad therapeutic applications, established clinical use, and extensive development pipeline across hematological, immune, orthopedic, and regenerative indications. The availability of donor-derived cells with potential for expansion, cryopreservation, and off-the-shelf use supports scalable manufacturing and treatment of multiple patients.
Intravenous Administration is Projected to Lead the Allogeneic Cell Therapy Market
- The intravenous-route sub-segment is anticipated to capture the largest share (30%) of the allogeneic cell therapy market in 2035. This is because it enables rapid and systemic distribution of therapeutic cells through the bloodstream, allowing them to reach multiple target tissues efficiently. Further, intravenous route is minimally invasive, clinically well-established, and ensures controlled, reproducible dosing with high cell viability compared to localized delivery methods. Additionally, intravenous administration supports natural mechanisms of cells to directly function on sites of injury or inflammation, making it suitable for a wide range of indications without the need for complex or site-specific delivery procedures. Further, this trend is likely to remain unchanged in the coming years as well
- The intradiscal route is anticipated to capture the second largest share of allogeneic cell therapy by 2035 due to its ability to overcome the limitations associated with intravenous administration by enabling targeted delivery of cells directly to the affected intervertebral disc.
Heart Failure Set to Lead Allogeneic Cell Therapy Industry
- By 2035, heart failure sub-segment is anticipated to emerge as the leading indication within the allogeneic cell therapy market. This growth is driven by the increasing global prevalence of heart failure and the lack of curative treatment options, which together create substantial demand for regenerative therapies.
- The degenerative disc disease is anticipated to capture the second-largest share of the allogeneic cell therapy market during the forecast period, due to the rising prevalence of age-related spinal disorders.
Cardiovascular disorders Sub-Segment is Likely to Capture the Largest Share
- The allogeneic cell therapies being used for cardiovascular disorders are anticipated to capture largest market share by 2035, supported by clinical development for heart failure and other cardiovascular conditions with substantial unmet need.
- The market for musculoskeletal disorders will capture the second largest highest share in allogeneic cell therapies by 2035 owing to the growing clinical development of allogeneic mesenchymal stem cell therapies for tissue regeneration and immunomodulation, coupled with their potential for scalable, off-the-shelf administration, is expected to support wider adoption.
Regional Market Insights
North America Dominates the Allogeneic Cell Therapy Market
North America is projected to remain the largest regional market through 2035, accounting for around 80% of global revenues. The region benefits form a dense biotechnology ecosystem, active clinical development, advanced manufacturing capabilities, academic-industry collaborations, investment availability and an established regulatory framework in the United States and other countries.
Allogeneic Cell Therapy Market Adoption in the Asia Pacific Region
Asia-Pacific is expected to expand substantially during the forecast period, growing at a CAGR of around 25%. Regional development is supported by cell therapies research and development, manufacturing investment and activity among companies such as Astellas Pharma and Sumitomo Pharma. The detailed methodology across the global allogeneic cell therapy market and revenue generated across various segments is available in the full report.
Key Players Profiled in the Allogeneic Cell Therapy Market
Examples of key companies profiled in this market report, arranged in alphabetical order, include Adicet Bio, Artiva Biotherapeutics, Cynata Therapeutics, CytoMed Therapeutics, Fate Therapeutics, Gamida Cell, Longeveron, Mesoblast, Ossium Health and Poseida Therapeutics. The complete list is available in the full report, together with a searchable Excel database of allogeneic cell therapy developers worldwide. Company names and trademarks are referenced solely for market-analysis and competitive-intelligence purposes; inclusion does not imply affiliation, endorsement or sponsorship by Roots Analysis.
Report Deliverables and Customization
Alongside the core market report, purchasers receive complimentary Excel data packs covering the allogeneic cell therapy market landscape, partnerships and collaborations analysis, funding and investment analysis, clinical trial analysis and market sizing and opportunity analysis. The report also includes a complimentary PowerPoint presentation summarizing the key findings and offers 15% free customization upon request. The analysis is designed to support pharmaceutical and biotechnology business-development teams, R&D and portfolio-strategy functions, manufacturing and CMC leaders, regulatory and quality teams, procurement and supply-chain functions, market-access teams, investors and company leadership evaluating clinical, manufacturing and commercial opportunities.
Report Authorship
Author(s): This report was co-authored by Rupali Vadhera and Pemba Lahmo, members of Roots Analysis healthcare and pharma research practice with experience in biologics discovery, development, and manufacturing market studies and competitive intelligence and market forecasting. Findings are based on proprietary databases, secondary research, regulatory analysis and executive interviews and are subject to internal review before publication.
This report is an independent work of market research and analysis published by Roots Analysis. It is not affiliated with, sponsored by, endorsed by, or reviewed by ENCell, Novartis, Allogene Therapeutics, S. Biomedics, Pharmicell, Mesoblast, or any other pharmaceutical company, drug brand, or regulatory body referenced within it. No content in this report should be construed as medical advice. Roots Analysis maintains its own proprietary primary research process and does not receive compensation from any company profiled within the report, in exchange for inclusion or favorable characterization.


