Blood Glucose Monitoring Devices Market by Type of Device (Continuous Glucose Monitoring Devices and Self-Monitoring of Blood Glucose Devices), Type of Diabetes (Type 1 Diabetes and Type 2 Diabetes), Component (Sensors and Transmitters, Testing Strips, Lancets and Lancing Devices, Receivers and Blood Glucose Meters), and Geographical Regions (North America, Europe, Asia-Pacific, Middle East and North Africa, and Latin America)- Trends and Forecast 2026-2035
Market Outlook
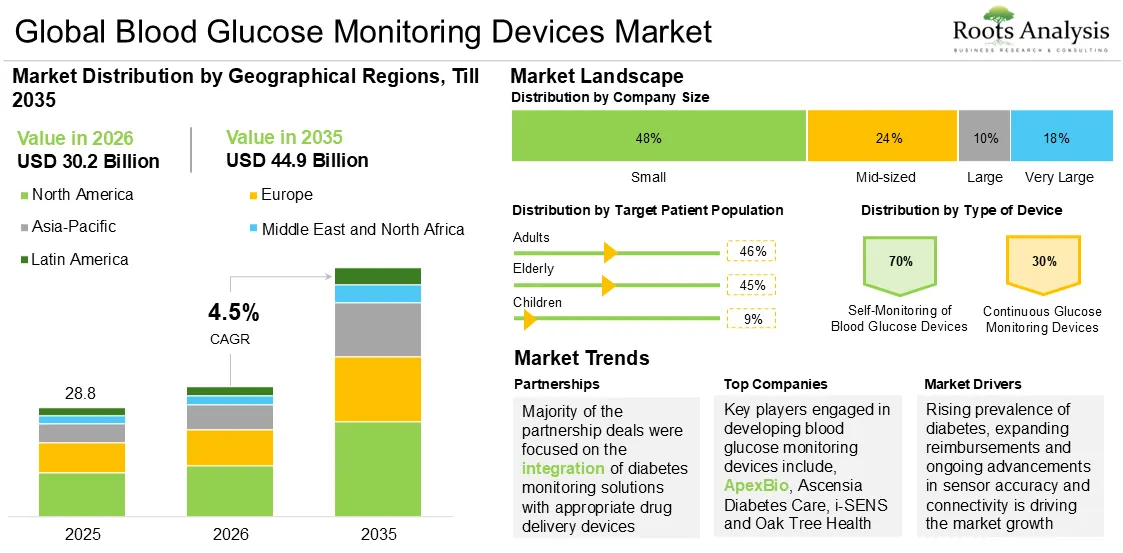
The global blood glucose monitoring devices market, valued at USD 28.8 billion in 2025, is projected to reach USD 30.2 billion in 2026 and USD 44.9 billion by 2035, representing a CAGR of 4.5% during the forecast period from 2026 to 2035. This growth is driven by the increasing global diabetes burden, broader clinical use of CGM, expanding reimbursement, over-the-counter access to selected CGM systems, improving sensor performance and increasing integration of glucose data with smartphones, digital-health platforms and automated insulin delivery technologies.
See What's in the Full Report – Request Your Complimentary Insights!
Market Report: Key Takeaways
Market Size & Trends
- Continuous glucose monitoring devices currently hold the largest share, accounting for close to 65% of the market share.
- Type 1 diabetes currently represents the leading segment, supported by lifelong insulin use, frequent glucose-monitoring requirements and higher penetration of CGM and automated insulin delivery technologies.
- Sensors and transmitters currently represent the largest component category within the CGM segment because sensors are recurring-use components and transmitters support continuous communication of glucose data.
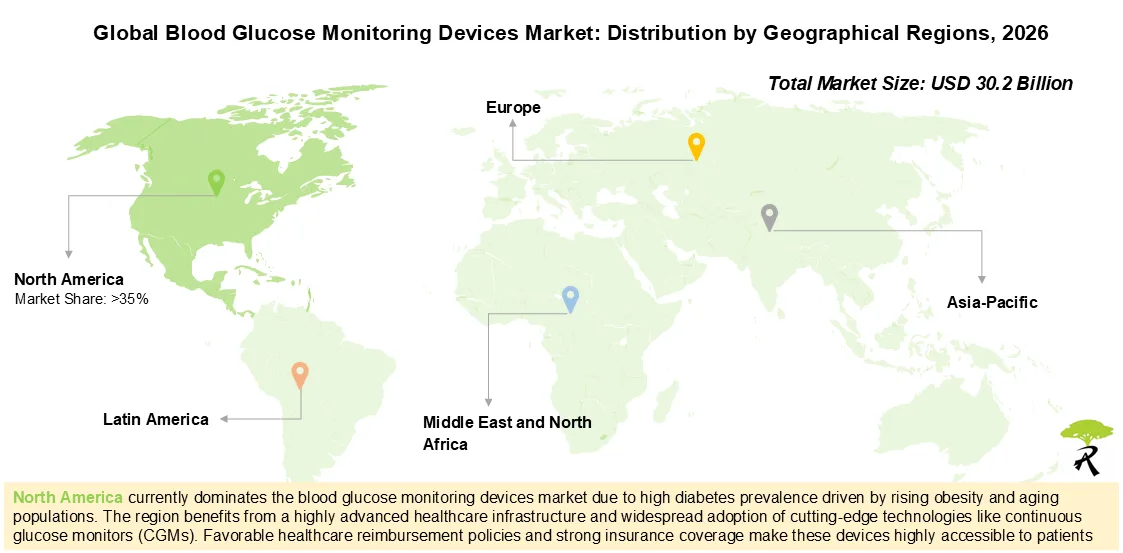
- North America currently captures more than 35% of the current market, while Asia-Pacific is likely to grow at a higher CAGR during the forecast period.
Key Market Statistics
- Market Size in 2026: USD 30.2 Billion
- Estimated Market Size in 2035: USD 44.9 Billion
- CAGR (2026 to 2035): 4.5%
- North America: Largest market in 2026
What are Blood Glucose Monitoring Devices?
Blood glucose monitoring devices help people with diabetes and healthcare professionals assess glucose levels, identify glycemic patterns and support treatment decisions. The market includes two principal device categories: self-monitoring of blood glucose systems, which use a blood glucose meter, test strips and lancets to measure capillary blood glucose at specific time points; and continuous glucose monitoring systems, which use a sensor to track glucose in interstitial fluid and provide repeated readings, trend information and alerts over time.
SBGM remains important for point-in-time testing, confirmation and many routine diabetes-management pathways. CGM provides a more continuous view of glucose patterns and is increasingly integrated with smartphones, cloud-based data platforms and automated insulin delivery systems. These differences make device type, component economics, reimbursement and user experience important considerations when evaluating the overall market.
According to the International Diabetes Federation, approximately 589 million adults aged 20-79 years are living with diabetes, and this number is projected to reach 853 million by 2050. The scale and chronic nature of the disease create sustained demand for accurate, accessible and easy-to-use glucose monitoring technologies.
Market Segmentation
The report segments the blood glucose monitoring devices market by type of device, type of diabetes, component and geographical regions.
By Type of Device
- Continuous Glucose Monitoring Devices, Self-Monitoring of Blood Glucose Devices
By Type of Diabetes
- Type 1 Diabetes, Type 2 Diabetes
By Component
- Sensors and Transmitters, Testing Strips, Lancets and Lancing Devices, Receivers, Blood Glucose Meters
By Geographical Regions
- North America, Europe, Asia-Pacific, Middle East and North Africa, Latin America
Your Business is Unique – Why Shouldn't Your Report Be?
Blood Glucose Monitoring Devices Market Key Insights
What are the Key Drivers for Blood Glucose Monitoring Devices Market Growth?
The expansion of CGM beyond its historical concentration in Type 1 diabetes and insulin-treated Type 2 diabetes is a major market driver. The American Diabetes Association Standards of Care in Diabetes-2026 recommend CGM at diabetes onset and anytime thereafter for people who could benefit from its use, reinforcing the role of glucose-sensing technologies across a broader range of diabetes-management pathways.
Access is also broadening through reimbursement and consumer availability. In the US, Medicare covers CGM for eligible people with diabetes who use insulin or have a history of problematic hypoglycemia, subject to clinical and training requirements. Separately, FDA clearances for over-the-counter systems such as Dexcom Stelo and Abbott Lingo / Libre Rio have expanded access to glucose sensing outside traditional prescription-only channels for defined user groups.
Technology integration is strengthening the value proposition of CGM. Wireless connectivity, mobile applications, cloud-based analytics and integration with automated insulin delivery systems allow glucose data to support dosing decisions, pattern recognition and remote review. These capabilities are moving glucose monitoring from isolated readings toward connected diabetes-management ecosystems.
What are the Main Challenges for Market Growth?
Despite strong demand, adoption of blood glucose monitoring devices is constrained by the recurring cost of sensors and supplies, uneven reimbursement, affordability differences across regions and the need for patient training. Device performance considerations such as sensor accuracy, reliability, calibration requirements for selected systems, skin irritation, data interruptions and alarm fatigue can also influence adherence and long-term use.
The shift toward increasingly connected devices introduces additional requirements around interoperability, software reliability, cybersecurity, data privacy and user experience. For manufacturers, regulatory compliance must therefore address not only the monitoring hardware but also software, connectivity and the broader digital ecosystem supporting device use.
Connected Glucose Monitoring, Interoperability and Digital Health
Continuous glucose monitoring systems are increasingly designed as connected platforms rather than standalone sensors. Data can be transmitted to smartphones or dedicated receivers, shared with caregivers and clinicians, and integrated with insulin pumps or automated insulin delivery systems. This connectivity can support trend visualization, alerts and more responsive diabetes-management decisions.
Digital-health functionality is also expanding beyond traditional diabetes treatment. Over-the-counter glucose biosensors and companion applications are creating new use cases for people not using insulin, while AI-enabled applications are being developed to convert continuous glucose data into more personalized summaries, pattern recognition and coaching. These adjacent use cases expand the commercial ecosystem but should remain clearly distinguished from regulated diabetes-treatment claims.
Payer, Reimbursement and Access Considerations
Reimbursement materially affects adoption because CGM requires recurring sensor supply and, in some systems, transmitter or receiver costs. In the US, Medicare Part B may cover CGM and related supplies for eligible beneficiaries with diabetes who use insulin or have a history of problematic hypoglycemia, while blood glucose meters, strips and lancets are also covered under defined DME rules. Private insurance coverage and national reimbursement policies vary across markets.
For patients and healthcare systems, the economic evaluation therefore extends beyond device acquisition cost. Coverage policy, frequency of sensor replacement, training requirements, pharmacy or DME distribution pathways, out-of-pocket expense and the potential for better glycemic management can all influence real-world uptake. The expansion of OTC CGM introduces a parallel consumer-access pathway for defined populations, but it does not replace prescription or reimbursed CGM for many people with diabetes.
Recent Developments in the Blood Glucose Monitoring Devices Market
- Abbott and Google: In August 2026, the companies announced a multi-year collaboration to integrate glucose insights from Abbott's Lingo biowearable with Google Health technologies and AI-enabled health coaching.
- Senseonics and Welldoc: In June 2026, the companies announced a strategic partnership to develop a next-generation mobile application for the Eversense 365 implantable CGM system, including enhanced integration with digital-health tools.
- Dexcom: In the US, FDA cleared Dexcom's Stelo Glucose Biosensor System for over-the-counter use in people two years of age and older who do not use insulin, expanding the age range of OTC glucose sensing in the US.
Blood Glucose Monitoring Devices Market: Scope, Methodology and Industry Expert Interviews
Roots Analysis defines the blood glucose monitoring devices market as the combined opportunity across self-monitoring of blood glucose (SMBG) and continuous glucose monitoring (CGM) systems, segmented by type of device, type of diabetes, component and geography, as detailed in the market segmentation above.
The opinions and insights presented in this study were influenced by discussions conducted with multiple stakeholders across the blood glucose monitoring devices value chain. These discussions informed the assessment of glucose monitoring practices, adoption of CGM and SBGM systems, patient preferences, reimbursement dynamics, technological advancements, distribution strategies, regulatory considerations, competitive positioning, and emerging commercial opportunities. These have been listed below:
- Founder and Chairman, Small Company, US
- General Manager- Business Development, Large Company, UK
In addition, the market report includes transcripts of the following other third-party discussions:
- Chief Executive Officer, and Chief Financial Officer, Mid-sized Company, US
- Chief Executive Officer, Large Company, US
- Chief Executive Officer, Small Company, US
- Chief Technology Officer and Co-Founder, Mid-sized Company, US
- Chief Operating Officer, Very Large Company, US
- Director of Education and Training in Diabetes, Very Large Organization, US
- Executive Vice President, Diabetes Care, Very Large Company, US
- Doctor, Sterile Consumables, Mid-sized Organization, US
- Clinical Associate Professor, Very Large Organization, US
- Clinical Associate Professor, Very Large Organization, US
- Clinical Lead for Diabetes, Very Large Organization, UK
Emphasizing the recent demand for advance CGM systems Tim Goodnow (Chief Executive Officer, Senseonics), stated that "About 90% of our product is coming from folks who have experience with [CGM]. It's in patients who are looking for more independence. We have a lot of emphasis in Medicare patients. Those tend to be people who have Type 2 diabetes. They're looking for a CGM where you don't have to deal with the hassle factor of a 10- to 14-day sensor. They don't have to change it. They don't have to deal with it if it comes off."
Pay Only for What You Need – The Best Way to Optimize
Market Share Insights
Which Type of Device Accounts for the Largest Share of the Blood Glucose Monitoring Devices Market?
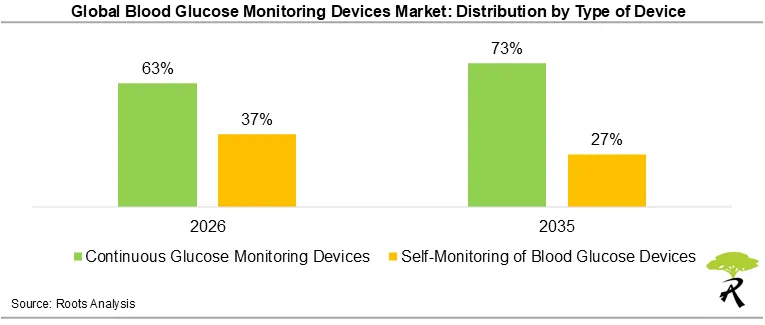
The continuous glucose monitoring devices segment currently occupies a very high market share (close to 65%) and is likely to grow at a higher CAGR during the forecast period. This is a result of increasing preference for real-time glucose tracking, reduced dependence on frequent finger-prick testing, growing adoption among insulin-treated patients, and greater integration of CGM systems with smartphones and automated insulin delivery technologies.
Amongst the Type of Diabetes, Which Segment Holds the Highest Share in the Blood Glucose Monitoring Devices Market?
The type 1 diabetes segment currently occupies the highest share in the overall blood glucose monitoring devices market; this is due to the lifelong dependence on insulin therapy and the consequent requirement for frequent glucose monitoring and CGM to optimize insulin dosing, maintain glycemic control, and reduce the risk of hypoglycemic and hyperglycemic events. The relatively higher penetration of CGM and automated insulin delivery systems among individuals with type 1 diabetes contributes to greater per-patient utilization and expenditure on glucose monitoring devices.
Which Component Holds the Largest Share of the Continuous Glucose Monitoring Devices Market?
Sensors and transmitters segment currently captures majority of the continuous glucose monitoring devices market share owing to the fact that sensors represent the most frequently replaced and recurring component of CGM systems, while transmitters are essential for continuously communicating glucose readings to compatible receivers or smartphones.
Which Regions are Showing the Fastest Growth?
North America Dominates the Market by Securing Highest Share
North America currently captures the largest share (more than 35%) of the blood glucose monitoring share primarily due to the high adoption of CGM systems in the US, favorable Medicare and private insurance coverage, early availability of over-the-counter CGMs, and a large diabetes population requiring regular glucose monitoring.
Asia-Pacific Emerged as a Growing Spot
The market in Asia-Pacific is likely to grow at a relatively higher CAGR owing to the rapidly expanding diabetic population, particularly in China and India. In addition, improving access to advanced diabetes technologies, expansion of private healthcare coverage, increasing patient awareness, and greater availability of glucose monitoring medical devices across major markets are likely to support faster regional growth during the forecast period.
Get an Instant Quote in 10 Minutes. Lowest Price Guaranteed
Key Players in the Blood Glucose Monitoring Devices Market
Examples of key companies profiled in this market report, arranged in alphabetical order, include ApexBio, Ascensia Diabetes Care, i-SENS, Oak Tree Health, SD Biosensor, TaiDoc Technology and VivaCheck Laboratories. The complete list of companies is available in the full report, which also includes an easily searchable Excel database of all the companies providing blood glucose meters worldwide. Additional named organizations referenced elsewhere in this report's underlying data, reflect funding and partnership activity tracked across the broader blood glucose monitoring ecosystem, not an endorsement relationship with Roots Analysis.
Report Deliverables and Customization
Alongside the core market report, purchasers receive complimentary Excel data packs covering the blood glucose monitoring device's market landscape, product competitiveness analysis, partnerships and collaborations analysis, big pharma initiatives, and market sizing and opportunity analysis. The report also includes a complimentary PowerPoint presentation summarizing the key findings and offers 15% free customization upon request.
Report Authorship
Author: This report was authored by Pemba Lahmo, part of Roots Analysis's healthcare and pharma research practice. Her work focuses on competitive intelligence, company benchmarking and market forecasting.
Independence and Non-Affiliation
Roots Analysis is an independent market research and consulting firm. This report draws on publicly available information, primary interviews, and proprietary analysis. Roots Analysis is not affiliated with, endorsed by, or a representative of the USFDA, the European Medicines Agency, or any of the companies, technologies, or individuals named in this report. All company and product names are used for identification purposes only and remain the property of their respective owners.
This report is the first edition covering the blood glucose monitoring devices space, reflecting continuous tracking of technological, regulatory, and commercial developments over the last 10 years. Roots Analysis maintains its own proprietary primary research process and does not receive compensation from any company profiled within the report, in exchange for inclusion or favorable characterization. Clients evaluating this report alongside competing market studies should weigh two factors in particular: whether the segmentation depth matches their specific decision, and whether the publisher discloses its own independence from the companies and regulatory bodies it covers.


