Market Size
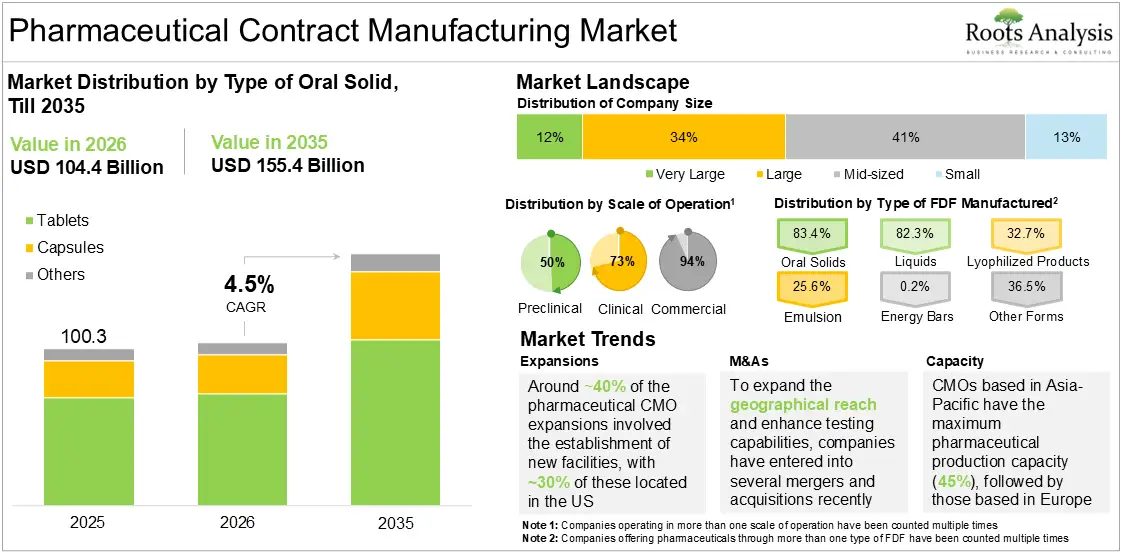
The global pharmaceutical contract manufacturing market size, valued at USD 100.3 billion in 2025, is projected to reach USD 104.4 billion in 2026 and USD 155.4 billion by 2035, with a CAGR of 4.5% during the forecast period 2026 to 2035. This market is growing steadily, driven by the increased extent of outsourcing, thereby accelerating the time-to-market.
To learn more about this report, request a free sample copy
Scope and Methodology
This report defines the pharmaceutical contract manufacturing market by outsourced product and service revenue across active pharmaceutical ingredients (API), intermediates and finished dosage forms (FDFs), covering originator and generic products for small-molecule and specialized dosage formats. The research combines secondary sources, proprietary databases, company disclosures, regulatory filings and structured interviews with several industry stakeholders, including executives, commercial, operational and technical leadership across the US, Switzerland, Israel, India, and France. Market estimates and shares were triangulated using manufacturing capacity, service portfolios, deal activity and regional demand.
- President and Chief Executive Officer, Corporate Strategy and Business Development, Mid-sized Company, US
- Former Chief Executive Officer, Large Company, Switzerland
- Former Vice President Business Development, Marketing, and IP, Mid-sized Company, Israel
- Director, Operations, Mid-sized Company, India
- Former Director of Business Development, Large Company, US
- Former Director, Commercial Development, Cell Therapy, Mid-sized Company, Switzerland
- Former Director, Pharmaceuticals Marketing, Large Company, France
- Digitalization and Artificial Intelligence Manager, Large Company, Switzerland
Primary interviews indicate that finished dosage form (FDF) outsourcing remains a central feature of pharmaceutical manufacturing strategies. Allison Vavala (Former Director of Business Development of Helsinn Group) stated, "Most pharma clients are outsourcing the manufacturing of drug products (FDF). This can be attributed to the fact that a lot of companies already have in-house drug substance manufacturing capabilities. In addition, some companies end up building their own facilities to produce the drug substance, while a product candidate is in the clinical development phases. Moreover, the drug substance manufacturing process takes more time. It can take a few months to manufacture the drug substance, whereas drug product manufacturing is usually a one-day task."
Market Segments
Based on the research, we have segmented the Pharmaceutical Contract Manufacturing Industry into type of product manufactured, type of API, API potency, type of FDF, dosage form, type of oral solid, type of packaging offered, scale of operation, end user, geographical regions, and key players.
- Type of Product Manufactured: API and Intermediates, FDF
- Type of API: Originator API, Generic API
- API Potency: Low Potent API, High Potent API
- Type of FDF: Originator FDF, Generic FDF
- Dosage Form: Oral Solids, Liquids, Emulsions, Other Dosage Forms
- Type of Oral Solid: Tablets, Capsules, Others
- Type of Packaging Offered: Bottles, Blister Packs, Vials, Prefilled Syringes, Cartridges, Ampoules, Oral Liquid Bottles, Others
- Scale of Operation: Clinical, Commercial
- End User: Small, Mid-sized, Large and Very Large
- Geographical Regions: North America (US, Canada), Europe (Spain, UK, Germany, Italy, France, Rest of the Europe), Asia-Pacific (India, China, Japan, South Korea, Australia, Rest of the Asia-Pacific), Latin America (Brazil, Argentina, Rest of Latin America), Middle East and North Africa (Saudi Arabia, Egypt, Rest of Middle East and North Africa)
What is Pharmaceutical Contract Manufacturing?
Pharmaceutical contract manufacturing refers to the outsourcing of drug development or manufacturing services to a third-party service provider, a Contract Manufacturing Organization (CMO), which produces goods under the label or brand of the client pharmaceutical company. Commonly outsourced processes include formulation design, dosage form development, clinical and commercial production, packaging, and distribution. Companies increasingly rely on CMOs for both active pharmaceutical ingredient (API) manufacturing and finished dose form (FDF) production, spanning GMP-compliant facilities that handle everything from oral solids to injectable formats such as vials, prefilled syringes, cartridges, and ampoules.
Market Report: Key Takeaways
- The increased extent of outsourcing by large pharma companies, growing demand for complex biologics and personalized medicine, and the need for specialized expertise is driving the demand for pharmaceutical contract manufacturing operations.
- API and Intermediates currently secure ~60% of the overall revenue share, owing to the increasing interest in API outsourcing driven by lower investment costs.
- In terms of the type of API, both originator and generic APIs capture almost equal share (around 50% each) of the current market; in the coming years, the market for generic API segment is anticipated to grow at a relatively faster pace.
- In terms of API potency, low potent API sub-segment currently holds around 85% of the market share, due to their widespread application, lower manufacturing complexity, and cost-efficient large-scale production.
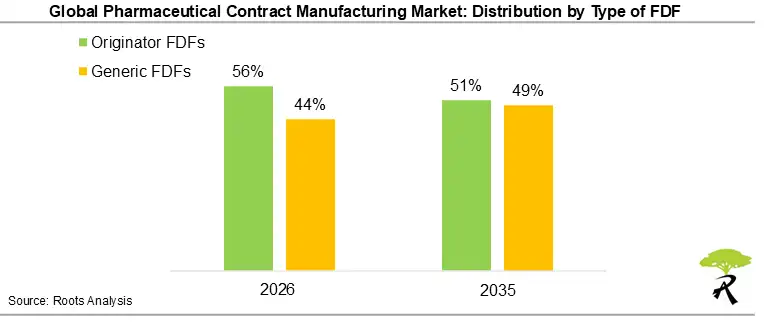
- In terms of type of FDF, originator FDFs currently capture around 55% of the overall FDF contract manufacturing market share, primarily due to established market presence and enhanced brand loyalty.
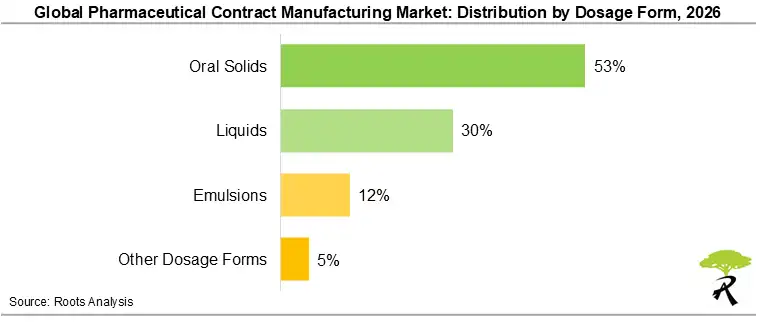
- With respect to dosage form, oral solids account for around 55% of the current market because they offer patient convenience, cost-efficient production and comparatively strong product stability.
- Tablets currently capture the largest share, at around 70%, driven by low manufacturing costs and the adoption of differentiated formats such as orally disintegrated tablets (OTDs) and bilayer tablets.
- With respect to type of packaging offered, bottles account for around 30% of the current market owing to their versatility across drug formats and ability to support product integrity, stability and patient safety.
- Commercial scale currently holds around 95% of the market share; clinical scale is anticipated to grow at a relatively faster pace owing to the increasing number of clinical trials and the growing focus on personalized medicines.
- In terms of end user, large and very large companies currently hold around 45% of the market share; the small companies segment is anticipated to grow at a relatively faster pace owing to the lack of well-established infrastructure in such companies.
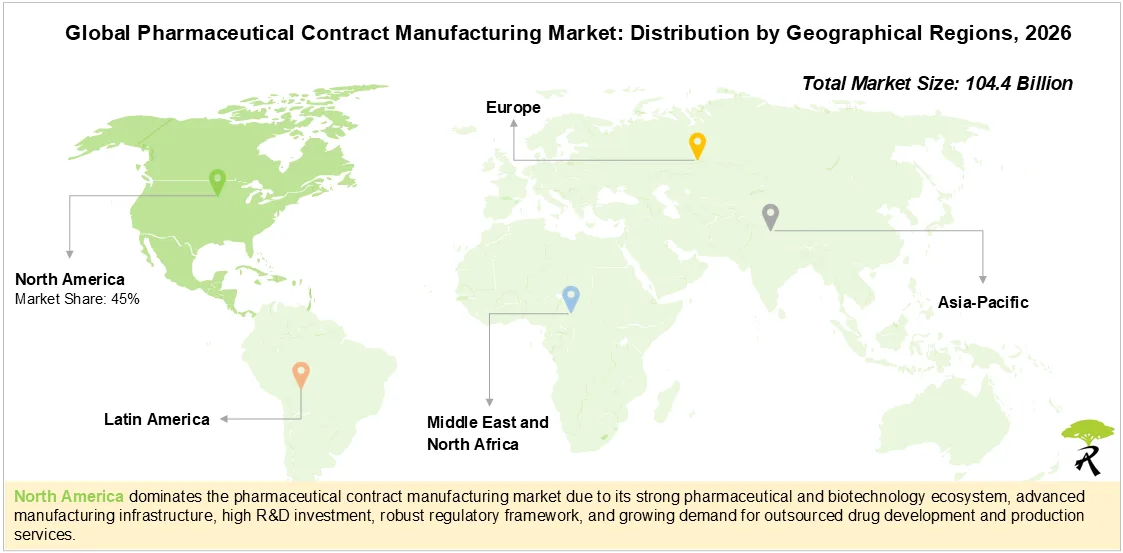
- North America holds around 45% of the current market share, reflecting a higher number of manufacturing facilities, as compared to other regions.
Key Market Statistics
- Market size in 2026: USD 104.4 Billion
- Estimated market size in 2035: USD 155.4 Billion
- CAGR (2026 to 2035): 4.5%
- API and Intermediates: around 60% revenue share
- Low potent API: around 85% share
- North America: around 45% share
Market Overview
The drug pipelines are becoming more complex, requiring specialized facilities, equipment and operational expertise. Sustained demand for advanced medicines is encouraging both emerging biotechnology companies and large pharmaceutical manufacturers, including generic and biosimilar developers, to outsource production to CMOs and CDMOs operating within FDA, EMA, and ICH regulatory frameworks.
CMOs and CDMOs are adopting continuous manufacturing, automation, data analytics, artificial intelligence and digital quality systems to improve process control and manufacturing efficiency. GMP-aligned quality management systems, data-integrity controls, validated processes, change control and end-to-end traceability are increasing importance for maintaining consistent quality and regulatory compliance.
Intellectual Property Protection in Outsourced Manufacturing
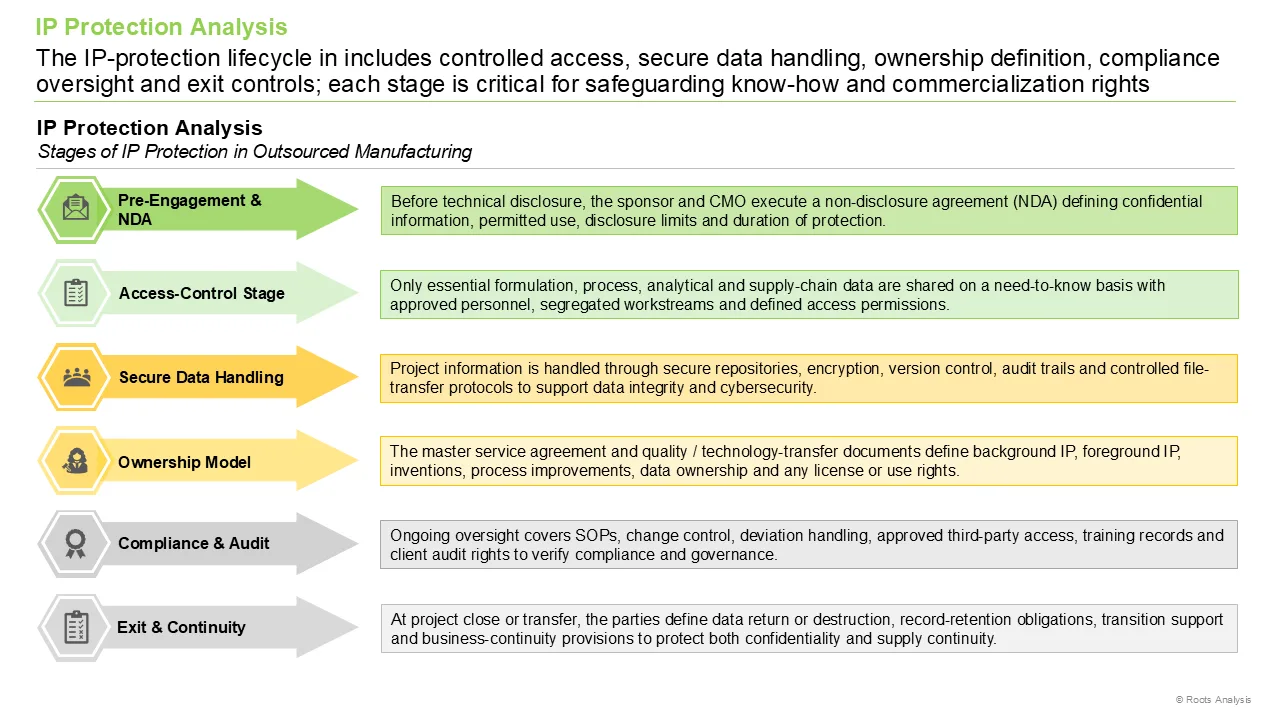
Outsourcing requires explicit controls for confidential formulations, process knowledge, analytical methods and manufacturing data. Pharmaceutical companies typically address these risks through non-disclosure agreements, quality and technology-transfer agreements, role-based data access, cybersecurity controls, clearly defined ownership of background and newly generated intellectual property, audit rights and contractual procedures for handling deviations and knowledge transfer.
Recent Developments
- In July 2026, Evonik announced a USD 100 million investment to modernize its drug-substance contract manufacturing facility in Lafayette, Indiana. The five-year program will upgrade reactors, automation systems and critical equipment to support increasingly complex small-molecule APIs and rising demand for US-based CDMO capacity.
- In July 2026, Resilience and Eli Lilly expanded their manufacturing partnership through a USD 750 million investment to increase US production of Lilly's KwikPen injectable devices for diabetes and obesity medicines.
- In April 2026, Eurofins CDMO Alphora integrated custom-built continuous-flow technology into its API manufacturing operations in Ontario, Canada. The equipment supports process intensification, improved control and safer scale-up for technically challenging APIs, extending the company's services from early process development through commercial production.
Pharmaceutical Contract Manufacturing Market Trends
- Mergers and Acquisitions: The market analysis shows several mergers and acquisitions, that are likely to drive the growth in this market. Such deals help the companies gain additional capability to offer a wider range of products and services, integrate new technologies and gain access to new markets or customer segments. For instance, Cohance (India) and Suven Pharma (India) entered into a merger in March 2025.
- Pharmaceutical Companies Expanding their Global Reach: In recent years, the pharmaceutical contract manufacturing industry has shown a notable increase in the number of players expanding their facilities in order to increase their global reach and gain additional expertise. A prime example is Bora Pharmaceuticals announcing the expansion of its facility to 100,000 square feet with an investment of USD 210 million.
- Growing Demand for Clinical-Scale and Lifecycle Manufacturing: Clinical-scale outsourcing is expanding as biotechnology companies seek flexible capacity for early-stage batches, while patent expires and lifecycle-management programs are increasing demand for generic APIs, genetic FDFs and biosimilar-related manufacturing support. CMOs that can scale programs from clinical to commercial production can reduce technology transfer risk and shorten timelines.
- Global Pharmaceutical Contract Production Capacity is Spread across Various Geographies: Globalization and the introduction of political and regulatory reforms have driven the advancement of pharmaceutical contract manufacturing services. These services now extend beyond developed geographies, reaching emerging markets as well. CMOs in Asia-Pacific currently have the maximum production capacity.
- Strategic Vendor Management and Supply-Chain Resilience: Procurement and sourcing teams are increasingly evaluating CMOs on regulatory track record, available capacity, lead times, geographic redundancy, qualified raw-material and packaging procurement, business-continuity planning and on-time delivery. Multi-sourcing and structured vendor governance can reduce disruption risk and strengthen supply-chain resilience.
Market Drivers
- Cost Efficiency and Flexibility in Time-to-Market: The operational flexibility provided by contract manufacturing organizations enables pharmaceutical companies to cater to the increased demand for pharmaceutical products by optimizing manufacturing processes at various scales and handling unforeseen challenges more effectively. Outsourcing also significantly helps pharmaceutical companies to reduce the overall cost associated with drug manufacturing.
- Growing Adoption of Advanced Technologies: The adoption of advanced technologies such as continuous manufacturing, automation, data analytics, and artificial intelligence by CDMOs ensures process efficiency, traceability, and real-time quality control under GMP-aligned quality management systems. These advancements allow CDMOs to efficiently produce complex therapeutics while establishing themselves as technological leaders in a highly competitive landscape.
Market Share Analysis
Manufacturing of Low Potent APIs is Most Widely Outsourced to Contract Manufacturing Organizations
The low potent API segment currently holds around 85% of the overall market share, primarily because these products are suitable for high-volume, scalable manufacturing and are widely used across chronic and infectious disease therapies.
The highly potent API (HPAPI) segment is expected to grow faster, supported by increasing demand for targeted therapies and precision medicines that require specialized containment, handling and manufacturing capabilities.
Oral Solid Dosage Forms Lead the Pharmaceutical Contract Manufacturing Industry with Unparalleled Demand
According to the pharma contract manufacturing market forecast, oral solid dosage forms accounts for around 55% of the overall revenue because of their affordability, patient convenience, product stability and suitability for large-scale production. The liquids segment is expected to show higher pharmaceutical contract manufacturing market growth.
Regional Analysis
North America Dominates the Pharmaceutical Contract Manufacturing Domain
North America dominates the pharmaceutical contract manufacturing domain, securing around 45% of the overall revenue share. A highly advanced pharmaceutical industry, strong regulatory frameworks, and the established presence of leading global drug manufacturers are boosting the demand for pharmaceutical contract manufacturers in the region.
US Pharmaceutical Contract Manufacturing Market
The US remains a leading pharmaceutical outsourcing hub owing to its large drug-development base, advanced manufacturing infrastructure, established quality systems and mature regulatory ecosystem. Demand is further supported by the need to manufacture therapies for a large and aging patient population with a high burden of chronic diseases.
Adoption of Pharmaceutical Contract Manufacturing Services in Asia-Pacific
Asia-Pacific is the fastest growing regional market, supported by competitive manufacturing costs, skilled technical talent, government incentives and expanding CMO capacity. Continued investment in China, India and South Korea, together with the adoption of advanced manufacturing and digital quality technologies, is strengthening the region's role in global pharmaceutical supply chains.
Capacity Analysis
Global pharmaceutical contract manufacturing capacity is distributed across facilities worldwide; with large and very large players accounting for more than 85% of total capacity. Capacity is distributed across North America, Europe, and Asia-Pacific and Rest of World, with Asia-Pacific currently holding the maximum production capacity.
Key Players
The pharmaceutical contract manufacturing market is served by a broad base of CMOs and API manufacturers. Companies profiled in the full report include Albemarle, Aspen Pharmacare, Bausch Health Sciences, Catalent, Delpharm, Eurofins Scientific, Evonik Industries, Fareva, Fresenius Kabi, Intas Pharmaceuticals, Lonza, Micro Labs, Nipro Patch, Patheon, PiSA Farmacéutica, Recipharm, Sandoz, West Pharmaceutical Services, Wockhardt, and WuXi AppTec, alongside recent-development subjects Aurobindo Pharma, AbbVie Contract Manufacturing, Fermion, Cohance, Suven Pharma, Bora Pharmaceuticals, and Lannett.
Report Deliverables and Customization
Alongside the core market report, clients receive complimentary Excel data packs covering market landscape analysis, mergers and acquisitions analysis, recent expansions analysis, capacity analysis, demand analysis, market forecast and opportunity analysis. A complimentary PowerPoint presentation summarizing the full report is also included, and 15% free customization scope is available on request.
Report Authorship
This report was authored by Simriti Gupta, member of Roots Analysis healthcare and pharmaceutical research practice. Her work focuses on drug development and manufacturing, competitive intelligence, company benchmarking and market forecasting.
Independence and Non-Affiliation
Roots Analysis is an independent secondary and primary market research publisher. This report is not affiliated with, endorsed by, or produced on behalf of any company named or profiled within it, including all key players, CDMOs, and industry expert interviewees referenced above.
Roots Analysis' findings draw on a combination of secondary research and primary interviews with industry experts, of the kind referenced above, to validate market sizing, segment shares, and forecast assumptions independently of any single company's disclosures.
Frequently Asked Questions
What is pharmaceutical contract manufacturer?
A pharmaceutical contract manufacturer is a third-party service provider responsible for producing drugs and other pharmaceutical products on behalf of pharmaceutical companies.How big is the pharmaceutical contract manufacturing market?
The global pharmaceutical contract manufacturing market was valued at USD 100.3 billion in 2025 and is projected to reach USD 104.4 billion in 2026 and USD 155.4 billion by 2035.What is the anticipated CAGR of pharmaceutical contract manufacturing market?
The global market is expected to grow at a compound annual rate of (CAGR) 4.5% from 2026-2035.Which region is expected to grow fastest in the pharmaceutical contract manufacturing market?
Asia-Pacific is likely to be the fastest growing regional market, supported by expanding manufacturing capacity, skilled talent, competitive operating costs and government support in China, India and South Korea.Which segment, in terms of type of product manufactured, currently accounts for the largest share of the market for pharmaceutical contract manufacturing?
The API and Intermediates segment currently holds the largest pharmaceutical contract manufacturing market share (around 60%).Which type of packaging is most widely used in the pharmaceutical contract manufacturing industry?
Bottles currently account for the largest share (around 30%) in the global pharmaceutical contract manufacturing market.How is intellectual property protected when manufacturing is outsourced?
Intellectual property is typically protected through non-disclosure agreements, quality and technology-transfer agreements, secure data controls, clearly defined ownership provisions, audit rights and contractual limits on the use or disclosure of confidential information.Is Roots Analysis affiliated with the companies profiled in this report?
Roots Analysis is an independent secondary and primary market research publisher. This report is not affiliated with, endorsed by, or produced on behalf of any company named or profiled within it, including all key players, CDMOs, and industry expert interviewees referenced above.