


 Download Free Sample
 Buy Now
Market Outlook
The global plasmid DNA manufacturing market, valued at USD 317 million in 2025, is projected to reach USD 395 million in 2026 and USD 2,689 million by 2035, representing a CAGR of 23.74% during the forecast period 2026 to 2035.
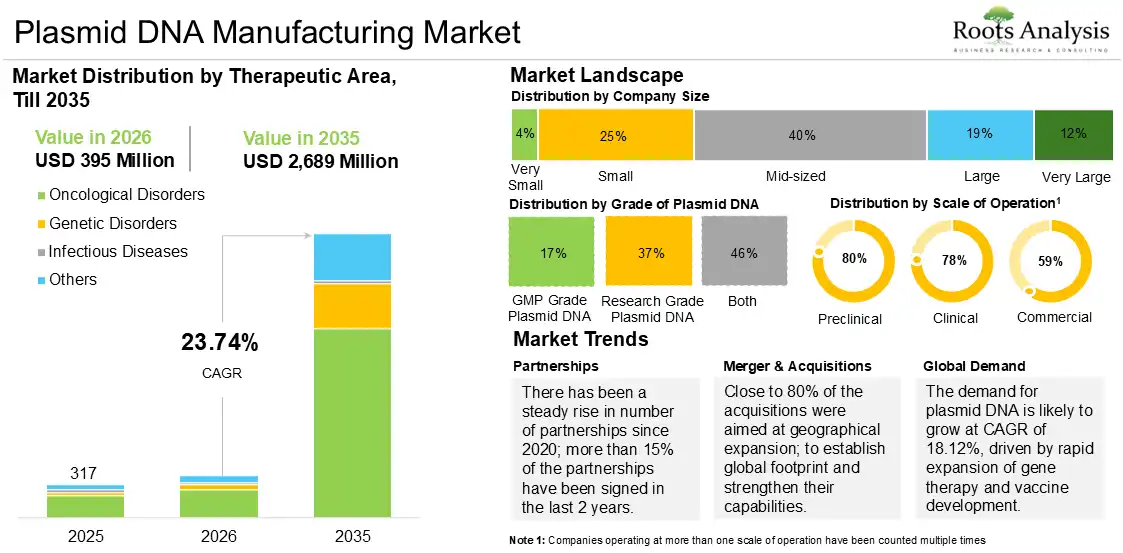
See What’s in the Full Report – Request Your Complimentary Insights!
Market Report: Key Takeaways
Market Size & Trends
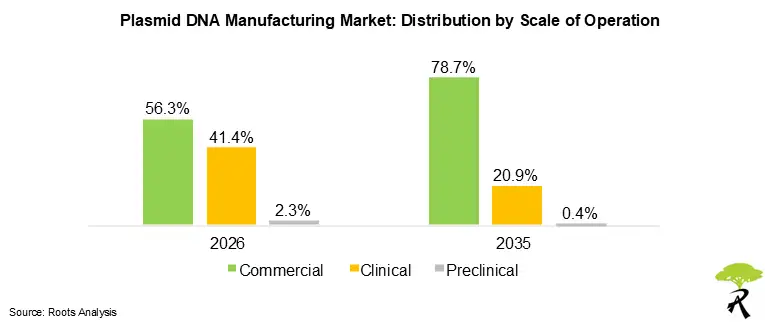
- The commercial scale segment captures the largest share (56.3%) of the current market, owing to the increasing number of approved gene therapies, mRNA vaccines, and other advanced therapies transitioning from clinical development to commercial production.
- GMP grade plasmid DNA segment captures the majority (74.3%) of the market share, and this trend is unlikely to change in the future as well.
- In terms of application area, viral vector manufacturing currently captures the largest share (50.2%) in the current market. This can be attributed to the critical role of plasmid DNA as a starting material in the production of viral vectors, such as adeno-associated viral vectors, lentiviral vectors, and adenoviral vectors.
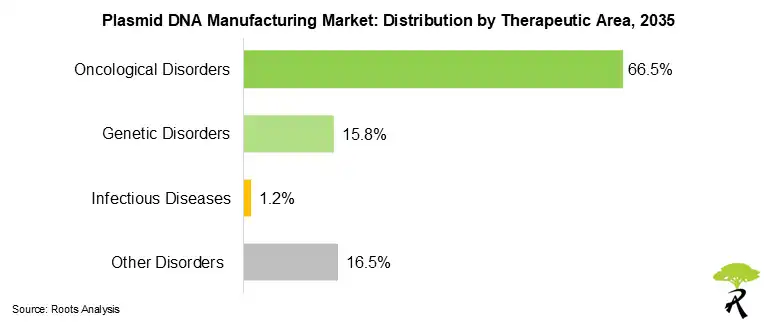
- Oncological disorders occupy the highest share (67.7%) in the overall market, due to the widespread prevalence of oncological disorders and the rapid expansion of gene therapy-based cancer treatments.
- In terms of end-user, the pharmaceutical companies and biotech companies are estimated to capture majority (80.7%) of the plasmid DNA manufacturing market.
- North America is estimated to capture majority (53.4%) of the plasmid DNA manufacturing market share.
Key Market Statistics
- Market Size in 2026: $395 Million
- Estimated Market Size in 2035: $2,689 Million
- CAGR (2026-2035): 23.74%
- North America: Largest market in 2026
- North America: Fastest-growing region
Market Introduction
Over the past few years, the plasmid DNA manufacturing market has emerged as a dynamic and rapidly growing sector that plays a pivotal role in biotechnology and genetic research. Plasmid DNA is a circular double-stranded DNA molecule that replicates independently of chromosomal DNA and can be genetically engineered for use in advanced therapy medicinal products (ATMPs) such as cell and gene therapies, as well as nucleic acid vaccines. The demand for plasmid DNA has grown significantly in recent years, primarily driven by the expanding clinical pipeline and commercialization of cell and gene therapies targeting cancers, rare genetic disorders, and other complex diseases. This growth is further fueled by rapid advancements in synthetic biology, CRISPR-based gene editing, high-yield GMP manufacturing processes, and increased outsourcing to specialized contract development and manufacturing organizations to support both clinical and commercial-scale production.
Despite its importance, plasmid production faces significant challenges including low yield, plasmid instability, and stringent regulatory requirements, which demand specialized GMP-compliant facilities. Researchers and drug developers are increasingly outsourcing to contract service providers that provide deep expertise in plasmid manufacturing. These specialized providers help streamline manufacturing, optimize resources, and ensure high-quality outputs that meet rigorous regulatory and research standards. With the rising demand for ATMPs and the growing preference for outsourcing, the plasmid DNA manufacturing market is poised for substantial growth in the coming years.
Market Segmentation
We have segmented the plasmid DNA manufacturing market into scale of operation, grade of plasmid DNA, application area, therapeutic area, end-user, and geography.
By Scale of Operation
- Commercial, Clinical, Preclinical
By Grade of Plasmid DNA
- GMP Grade Plasmid DNA, High Quality Plasmid DNA, Research Grade Plasmid DNA
By Application Area
- Viral Vector Manufacturing, Gene Therapy Manufacturing, Cell Therapy Manufacturing, DNA Vaccine Manufacturing, mRNA Vaccine Manufacturing
By Therapeutic Area
- Oncological Disorders, Genetic Disorders, Infectious Disorders, Other Disorders
By End-user
- Pharma / Biotech Companies, Academic and Research Institutes, Other End-users
By Geography
- North America, Europe, Asia-Pacific, Latin America, Middle East and North Africa, Rest of the World
Your Business is Unique – Why Shouldn’t Your Report Be?
Plasmid DNA Manufacturing Market Key Insights
What are the Key Drivers for Plasmid DNA Manufacturing Market Growth?
- Rising Demand for Gene and Cell Therapies: The rapid expansion of the clinical pipeline for gene therapies, cell therapies (including CAR-T), and personalized medicine is the primary growth driver of the plasmid DNA manufacturing market. Plasmid DNA serves as a critical starting material and vector for these advanced therapies. With hundreds of therapies in development and several approvals, the need for high-quality, GMP-grade plasmid DNA has surged significantly.
- Growing Need for Nucleic Acid Vaccines: The success of plasmid-based platforms during the COVID-19 pandemic (used by companies like Moderna and Pfizer-BioNTech) highlighted their importance in rapid vaccine development. This has driven sustained demand for plasmid DNA in DNA / RNA vaccines, infectious disease research, and future pandemic preparedness.
- Increasing Outsourcing to Contract Development and Manufacturing Organizations: Due to the complexities of plasmid production (low yields, instability, and strict regulatory / GMP requirements), biopharma companies are increasingly relying on specialized contract service providers. This trend allows faster scale-up, process optimization, and access to advanced technologies without heavy in-house investment.
What are the Main Challenges for Market Growth?
- Scale-up Challenges: Service providers capable of delivering GMP grade plasmid DNA continue to face substantial waiting lists and production backlogs due to rising demand. The inability to supply quality plasmid within stringent timelines poses risks, potentially impeding progress in R&D pipelines, impacting market expectations, and compromising patient care outcomes.
- Industry Concentration: The plasmid DNA manufacturing services market is currently dominated by well-established players, creating significant challenges for small companies striving to establish their presence. Such players often encounter obstacles, including business failure, or acquisition by other dominant players.
- Limited Availability of Skilled Workforce: The plasmid DNA manufacturing industry relies heavily on specialized expertise and advanced equipment, and the limited availability of a skilled workforce can lead to hindrance in productivity, and output. Moreover, lack of proper expertise increases the risk of errors, compromising integrity of the final product.
Recent Developments in Plasmid DNA Manufacturing Market
- In April 2026, Novel Bio entered into an agreement with Wyvern Pharmaceuticals to supply high quality grade plasmid DNA to support Wyvern's development of a personalized or targeted therapy for late-stage cancer patients.
- In February 2026, Scarab Genomics entered into a licensing agreement with Bionova to utilize one of Scarab’s proprietary Clean Genome strains for plasmid DNA (pDNA) production.
- In January 2026, Charles River Laboratories entered into a manufacturing agreement with Gazi University to provide plasmid DNA for AAV production and in vitro efficacy studies.
Scope, Methodology and Industry Experts Interviews
Roots Analysis segments the plasmid DNA manufacturing market report by scale of operation, grade of plasmid DNA, application area, therapeutic area, end-user, and geographical regions. Driven by the growing pipeline of cell and gene therapy candidates, the plasmid DNA manufacturing domain is going to grow in the near future.
Frenk Smrekar (Chief Executive Officer and Co-Founder, JAFRAL Biosolutions), stated that, “North America captures the largest share of the global plasmid DNA manufacturing market. Furthermore, Asia and Europe are expected to emerge as valuable contributors to the global plasmid DNA manufacturing market. This is followed by the Middle East and North Africa, Latin America, and the rest regions of the world.”
Discussions with multiple stakeholders in this domain influenced the opinions and insights presented in this study. The market report includes transcripts of the following discussions:
- Chief Executive Officer and Co-Founder, Small Company, Slovenia
- Senior Director, Large Company, US
- Senior Director Commercial, Small Company, Germany
- Business Development Manager, Mid-sized Company, Spain
- Client Engagement Manager, Mid-sized Company, US
In addition, the market report includes transcripts of the following other third-party discussions:
- Founder, Small Company, UK
- Chief Scientific Officer, Mid-sized Company, UK
- Associate Director, Large Company, US
- Senior Vice President & General Manager, Mid-sized Company, US
- Vice President, Corporate Development, Large Company, US
- Senior Scientist, Small Company, US
- Process Development Scientist, Mid-sized Company, US
- Head of Manufacturing GMP Grade, Small Company, Germany
- Chief Technical Officer, Small Company, US; Founder, Small Company, UK; Senior Consultant, Mid-sized Company, US and Chief Technical Operations Officer, Mid-sized Company, UK
- Technical Support for Plasmid DNA Platform, Large Company, US
- Global CMC Manager, Large Company, Germany
Pay Only for What You Need – The Best Way to Optimize
Market Share Insights
Commercial Scale Dominates the Plasmid DNA Manufacturing Market
The commercial segment occupies the highest share in the plasmid DNA manufacturing market (56.3%) in 2026 and is likely to grow at a relatively higher CAGR (28.44%) during the forecast period. This growth can be attributed to the increasing number of therapies progressing from clinical trials to regulatory approvals for various target indications.
GMP Grade Plasmid DNA Segment Holds the Largest Market Share of Plasmid DNA Manufacturing Market
The GMP grade plasmid DNA segment currently occupies the highest plasmid DNA manufacturing market share (74.3%) owing to the critical requirement for GMP-certified plasmid DNA in clinical trials and commercial manufacturing of gene therapies, viral vectors, and nucleic acid-based vaccines to meet regulatory standards.
Viral Vector Manufacturing Dominates the Plasmid DNA Manufacturing Market
Viral vector manufacturing currently captures the maximum share (50.2%) of the overall market and is likely to grow at a relatively higher CAGR (27.95%) during the forecast period. This is due to the critical and high-volume requirement for GMP-grade plasmid DNA as an essential starting material for producing viral vectors used in gene therapies. This segment is further driven by a strong clinical pipeline, increasing commercial approvals, and the need for kilogram-scale plasmid quantities in large bioreactor-based manufacturing processes.
Oncological Disorders Hold the Largest Market Share in Plasmid DNA Manufacturing Market
Oncological disorders occupy the highest plasmid DNA manufacturing market share (67.7%), owing to the high economic burden imposed by the continuous increase in cancer prevalence, necessitating the need for advanced therapies. The genetic disorders segment is likely to grow at a relatively higher CAGR (29.10%) during the forecast period due to the rapid expansion of gene therapy-based treatments for rare genetic diseases.
Pharmaceutical and Biotechnology Companies Dominate the Plasmid DNA Manufacturing Market
The pharmaceutical and biotechnology companies currently occupy the highest share in the plasmid DNA manufacturing market (80.7%). This is a result of the significant investments and strategic capacity expansions by pharmaceutical and biotechnology companies to secure plasmid DNA supply and the increasing number of pharma / biotech companies entering the gene therapy space.
Market Regional Insights
North America Dominates the Plasmid DNA Manufacturing Market
North America currently captures majority (53.4%) of the plasmid DNA manufacturing market share and is likely to grow at a relatively higher CAGR (28.32%), during the forecast period. This can be attributed to the increasing number of approvals of gene therapies in the region, leading to a surge in demand for plasmid DNA.
Get an Instant Quote in 10 Minutes. Lowest Price Guaranteed
Scope of Plasmid DNA Manufacturing Market Report
| Key Report Attributes | Details | |
| Segments Covered |
|
|
| Excel Data Packs (Complimentary) |
|
|
| PowerPoint Presentation (Complimentary) |
|
|
| Customization Scope |
|
|
Key Players
The report profiles AGC Biologics, Aldevron (acquired by Danaher), Catalent Pharma Solutions, Charles River Laboratories, GenScript ProBio (a subsidiary of GenScript), PackGene Biotech, Sartorius, VectorBuilder, VGXI, and WuXi ATU.
Report Authorship
This report was co-authored by Simriti Gupta and Nancy Kapila, members of Roots Analysis healthcare and pharmaceutical research practice. Their work focuses on competitive intelligence, company benchmarking and market forecasting.
Independence and Non-Affiliation
Roots Analysis is an independent secondary and primary market research publisher. This report is not affiliated with, endorsed by, or produced on behalf of any company named or profiled within it, including all key players and industry expert interviewees referenced above.
Roots Analysis' findings draw on a combination of secondary research and primary interviews with industry experts, of the kind referenced above, to validate market sizing, segment shares, and forecast assumptions independently of any single company's disclosures.


