Digital Biomanufacturing Market by Type of Technology (Manufacturing Execution Systems, Process Analytical Technologies, Data Analytics Software and Digital Twins), Deployment Option (Cloud-based Deployment and On-premises Deployment), Scale of Operation (Commercial Scale and Clinical Scale), Type of Biologic Manufactured (Antibodies, Peptides, Cell and Gene Therapies, and Other Biologics), End Users and Geographical Regions – Trends and Forecast 2026-2035
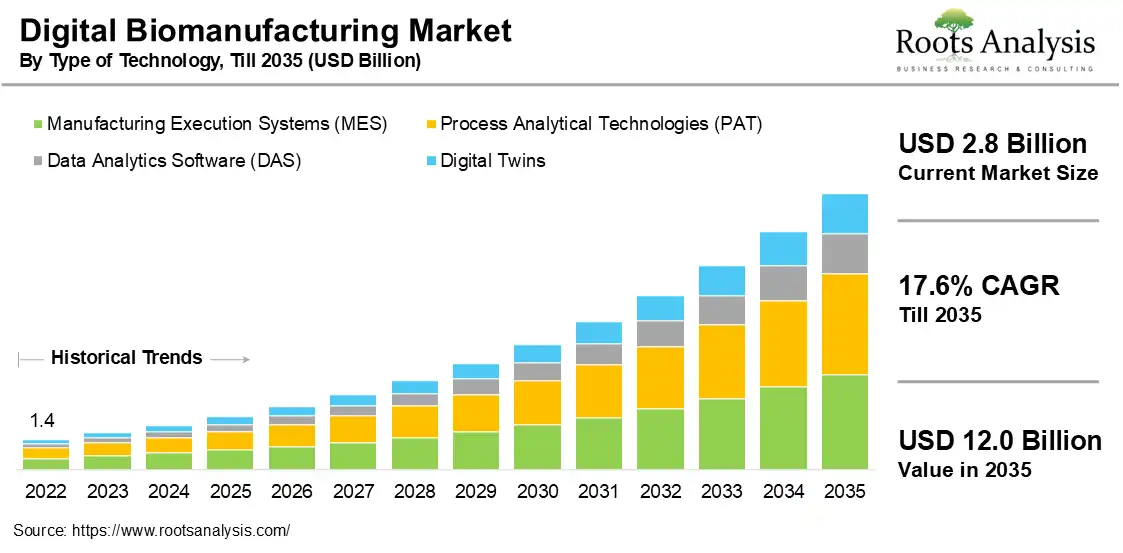
Digital Biomanufacturing Market Outlook: USD 12.0 Billion by 2035 at a 17.6% CAGR
The global digital biomanufacturing market, valued at $2.4 billion in 2025, is projected to reach $2.8 billion in 2026 and $12.0 billion by 2035, representing a CAGR of 17.6% during the forecast period 2026 to 2035.
See What's in the Full Report – Request Your Complimentary Insights!
Market Report: Key Takeaways
Market Size & Trends
- In terms of type of technology, the manufacturing execution systems (MES) segment holds the largest share of the market, at nearly 35%.
- With respect to deployment option, the on-premises segment currently holds more than 65% of the market, while cloud-based deployment is expected to grow at a faster rate.
- Based on type of biologic manufactured, antibodies account for the largest share, at 70%, while the cell and gene therapies segment is expected to grow fastest, at a CAGR of 29%.
- In-house developers currently capture nearly 65% of the market by end user, while contract manufacturers are expected to grow at a comparatively faster pace.
- Commercial-scale operations hold the largest share of the market, at approximately 90%, and are expected to remain dominant through the forecast period.
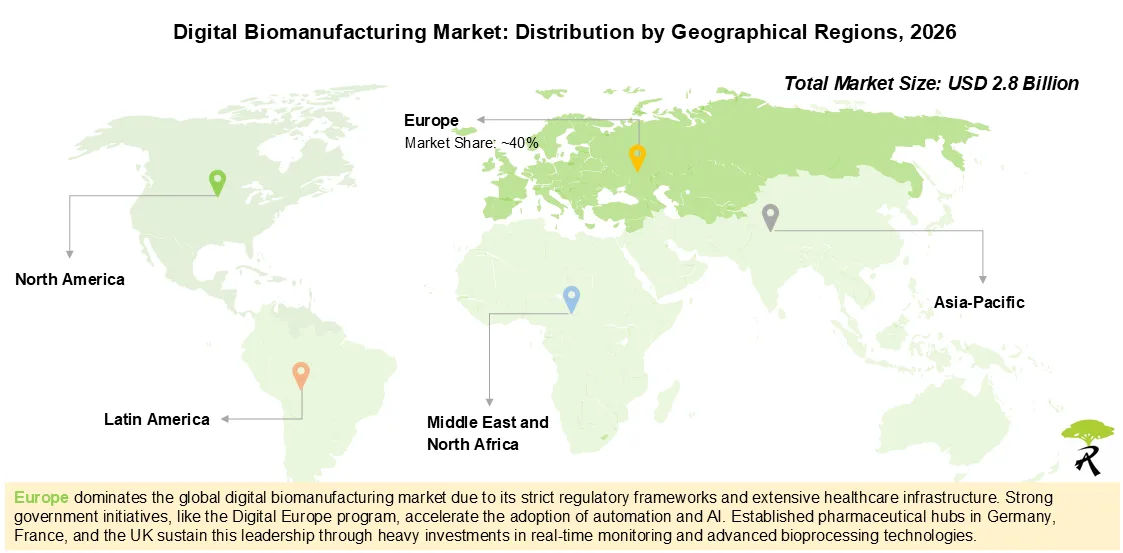
- Europe leads the market by geography, capturing close to 40% of the current share, while Asia-Pacific is expected to be the fastest-growing region.
Key Market Statistics
- Market Size in 2026: $2.8 Billion
- Estimated Market Size in 2035: $12.0 Billion
- CAGR (2026-2035): 17.6%
- Europe: Largest market in 2026
- Asia-Pacific: Fastest growing region
What is Driving Digital Biomanufacturing Market Growth Through 2035?
Biologics manufacturing requires substantial investment across development and production because of complex molecules, specialized facilities and stringent quality requirements. These factors are increasing pressure on biopharmaceutical companies to improve production efficiency, product quality and manufacturing timelines. This pressure is accelerating the shift from conventional manufacturing operations toward digital biomanufacturing, or bioprocessing 4.0, built around Industry 4.0 technologies, automation and connected process-control systems.
Several biopharmaceutical companies using digital biomanufacturing report improvements in product quality, process consistency, operating cost and production timelines, strengthening the business case for wider adoption.
Digital biomanufacturing integrates physical manufacturing equipment with digital technologies and software, including process analytical technology (PAT), data analytics software (DAS), manufacturing execution systems (MES) and digital twins, to monitor and control biomanufacturing workflows. Continuous manufacturing systems can further integrate material handling, process control and quality monitoring into uninterrupted production lines.
Companies are increasingly deploying PAT and data analytics software for process monitoring, MES for production execution and electronic records, and digital twins to model and optimize manufacturing performance. Digital infrastructure is also being combined with single-use technologies and automated bioprocess equipment to support flexible manufacturing of vaccines, monoclonal antibodies, cell and gene therapies and other biologics.
Regulatory expectations are also shaping adoption. For US manufacturing operations, applicable U.S. Food and Drug Administration (FDA) requirements around current good manufacturing practice, validated computerized systems, data integrity and traceable electronic records reinforce the need for controlled and auditable digital manufacturing platforms.
Scope, Methodology and Industry Experts Interviews
The study combines secondary research, publicly available company and technology information, market analysis and primary discussions with industry stakeholders to validate market assumptions, technology adoption trends, competitive-landscape findings and forecast estimates. The report also features detailed transcripts of interviews conducted with the following industry stakeholders (arranged in decreasing order of seniority level):
- Chief Executive Officer, Founder and President, Small Company, Canada
- Former Chief Executive Officer and Managing Director, Small Company, Germany
- Former Vice President of Operations and Strategic Initiatives, Mid-sized Company, US
- Regional Sales Director, Asia-Pacific, and Quality and Manufacturing Digitization Specialist, Large Company, US
- Former Director of Sales, Mid-sized, Israel
- Business Consultant, Very Large Company, France
Your Business is Unique – Why Shouldn't Your Report Be?
How Is the Digital Biomanufacturing Market Segmented?
Based on the research, we have segmented the market into type of technology, deployment option, scale of operation, type of biologic manufactured, end users, and geographical regions.
- By Type of Technology: Manufacturing Execution Systems (MES), Process Analytical Technologies (PAT), Data Analytics Software (DAS), and Digital Twins
- By Deployment Option: Cloud-based Deployment and On-premises Deployment
- By Scale of Operation: Commercial Scale and Clinical Scale
- By Type of Biologic Manufactured: Antibodies, Peptides, Cell and Gene Therapies, and Other Biologics
- By End Users: In-house Developers, Contract Manufacturers, and Both
- By Geographical Regions: North America (US and Canada), Europe (Germany, France, Italy, Spain, UK and Rest of the Europe), Asia-Pacific (China, India and Japan and Rest of Asia-Pacific), Middle East and North Africa (Saudi Arabia, United Arab Emirates and Egypt), and Latin America (Brazil, Mexico and Argentina)
Recent Developments in Digital Biomanufacturing Market
- In May 2026, Digital Tvilling and Curve entered into a partnership with an aim to combine Curve's precision fermentation and continuous data collection technologies with Digital Tvilling's graph-based modelling, agentic AI and data infrastructure capabilities.
- In March 2026, Stämm launched a High-Throughput Bioprocessor (HTB), an automated, single-use biomanufacturing platform for adherent and suspension cells. This bioprocessor aims to accelerate the development process of biologics and cell & gene therapies.
- In March 2026, Bota launched SAION AI, a full-stack "Physical AI" platform for biomanufacturing that integrates cognition, orchestration, and execution layers. The system combines large language models with closed-loop experimentation to optimize biological discovery and manufacturing processes, representing a shift from in silico modeling to real-world automated and adaptive biomanufacturing systems.
Market Share Insights
Which Type of Technology Leads the Digital Biomanufacturing Market?
Manufacturing execution systems currently hold the largest share of the digital biomanufacturing market, at nearly 35%, supported by adoption among mid-sized and large biomanufacturers seeking real-time visibility into production data and greater operational flexibility. The integration of automated solutions such as manufacturing execution systems into bioproduction lines enables full access to real-time production data and better analysis of the manufacturing processes.
On the other hand, the process analytical technology segment is anticipated to grow at a relatively higher growth rate, during the given time period, owing to their ability of PAT systems in identifying and mitigating the risks associated with manufacturing at an early stage. Several manufacturers are seeking expert opinions on how to implement analytical technology processes in biomanufacturing.
Will Commercial-Scale Manufacturing Continue to Dominate?
The market is dominated by the revenues generated from digital manufacturing of biologics at commercial scale, capturing around 90% of the market share. Further, owing to the likely approvals of various biologics in the late stage of development in the coming years, this trend is expected to remain the same during the forecast period.
Which Type of Biologic Is Driving Market Share?
Antibodies, including monoclonal antibodies, currently account for 70% of the market, reflecting the large installed base of approved antibody products and established commercial manufacturing processes. The market for digitally manufactured cell and gene therapies is anticipated to grow at a relatively higher CAGR, during the given time period, reflecting the increased adoption of digitalization by industry players, for achieving operational excellence in the field of cell and gene therapy manufacturing.
Is On-premises Deployment Losing Ground to the Cloud?
On-premises deployment currently accounts for more than 65% of the market, supported by data-security, privacy and operational-control requirements within biomanufacturing facilities.
Cloud-based deployment is anticipated to grow at a relatively higher growth rate, due to the fact that implementation of cloud software enables businesses to access software services remotely without huge investments in the infrastructure.
Will In-house Developers Continue to Lead by End User?
In-house developers currently hold nearly 65% of the market by end user, reflecting the preference of larger biomanufacturers to retain process automation, optimization and end-to-end manufacturing control within their own operations.
Contract manufacturers are expected to grow at a comparatively faster pace as biopharmaceutical companies increasingly rely on contract manufacturing organizations (CMOs) and contract development and manufacturing organizations (CDMOs) for external biologics capacity, specialist expertise and digitally enabled production.
Regional Analysis of Digital Biomanufacturing Market
Why Does Europe Lead the Digital Biomanufacturing Market?
Europe is expected to capture close to 40% of the market, the largest regional share, supported by a strong base of established biomanufacturing companies and digital infrastructure. Asia-Pacific is expected to be the fastest-growing region as manufacturers increase investment in digitized production capabilities. The detailed methodology across the global digital biomanufacturing market and revenue generated across various segments is available in the full report.
Pay Only for What You Need – The Best Way to Optimize
Key Market Insights
What Advantages Does Digital Biomanufacturing Offer?
Digital biomanufacturing allows real-time monitoring, data analytics, automation, modelling and process optimization, supporting the transformation of data into actionable insights. This allows biomanufacturers to develop a uniform process and reduce the variation in product quality across each batch, in order to achieve batch-to-batch consistencies.
Moreover, innovative technologies, such as AI and digital twins, have become an integral part of the manufacturing process development strategy, to future-proof their business operations and address various issues, including growing manufacturing expenses, stringent regulatory guidelines and deteriorating profit margins. Several companies have followed the best practices for healthcare digital twins, especially biomanufacturing, and have gained benefit.
What Does the Current Digital Biomanufacturing Provider Landscape Look Like?
The current market landscape includes more than 135 digital technologies and software platforms offered by industry stakeholders. Measured by the number of technologies / software platforms offered, process analytical technologies account for nearly 40% of the landscape, followed by manufacturing execution systems and data analytics software. These figures describe provider-platform counts and should not be interpreted as market revenue shares. Within this workflow, MES platforms coordinate electronic batch records, materials, equipment and quality data on the production floor.
The provider landscape remains fragmented, with more than 100 companies offering digital biomanufacturing technologies. Small and mid-sized companies account for a large proportion of providers, while close to 55% of companies were established before 2005, indicating a mix of established suppliers and newer entrants.
Roots Analysis is an independent market research and consulting firm. Companies referenced in this landscape discussion are named solely for research and benchmarking purposes; inclusion does not imply endorsement, partnership or any business relationship with Roots Analysis.
Get an Instant Quote in 10 Minutes. Lowest Price Guaranteed
Key Players Profiled in Digital Biomanufacturing Market
The digital biomanufacturing market is served by a broad base of companies. Companies profiled in the full report include Apprentice, AspenTech, CellPort, Dassault Systèmes, Eppendorf, FUJIFILM Diosynth Biotechnologies, GE Vernova, Körber, Merck, Sartorius, Siemens, Striim, Thermo Fisher Scientific, Tridiagonal Software, and Vimachem. A complete list of 390+ companies captured is available within the full report.
Report Deliverables and Customization
Alongside the core market report, clients receive complimentary Excel data packs covering market landscape analysis, technology competitiveness analysis, benchmark analysis, partnerships and collaborations and market forecast and opportunity analysis. A complimentary PowerPoint presentation summarizing the full report is also included, and 15% free customization scope is available on request. The report is designed to support pharmaceutical business development, procurement, R&D and regulatory affairs teams evaluating outsourcing partners, as well as CMOs and CDMOs benchmarking their capabilities, capacity and competitive positioning.
Report Authorship
Author: Pemba Lahmo, Healthcare and Pharmaceutical Research Practice, Roots Analysis
Her work focuses on competitive intelligence, company benchmarking and market forecasting.
Independence and Non-Affiliation
Roots Analysis is an independent secondary and primary market research publisher. This report is not affiliated with, endorsed by, or produced on behalf of any company named or profiled within it, including all key players, and industry expert interviewees referenced above.
Roots Analysis' findings draw on a combination of secondary research and primary interviews with industry experts, of the kind referenced above, to validate market sizing, segment shares, and forecast assumptions independently of any single company's disclosures.


