GLP-1 Receptor Agonist Market by Type of Molecule (Biologics and Small Molecules), Active Compound Used (Dulaglutide, Liraglutide, Orforglipron, Retatrutide, Semaglutide, Survodutide, Tirzepatide, Other Active Compounds), Type of GLP-1 Agonist Drugs (Long-acting GLP-1 Agonist and Short-acting GLP-1 Agonist), GLP-1 Agonist, Route of Administration, Target Indication, Geographical Regions, Sales Forecast and Leading Drug Developers – Trends and Forecast 2026-2035
Market Outlook
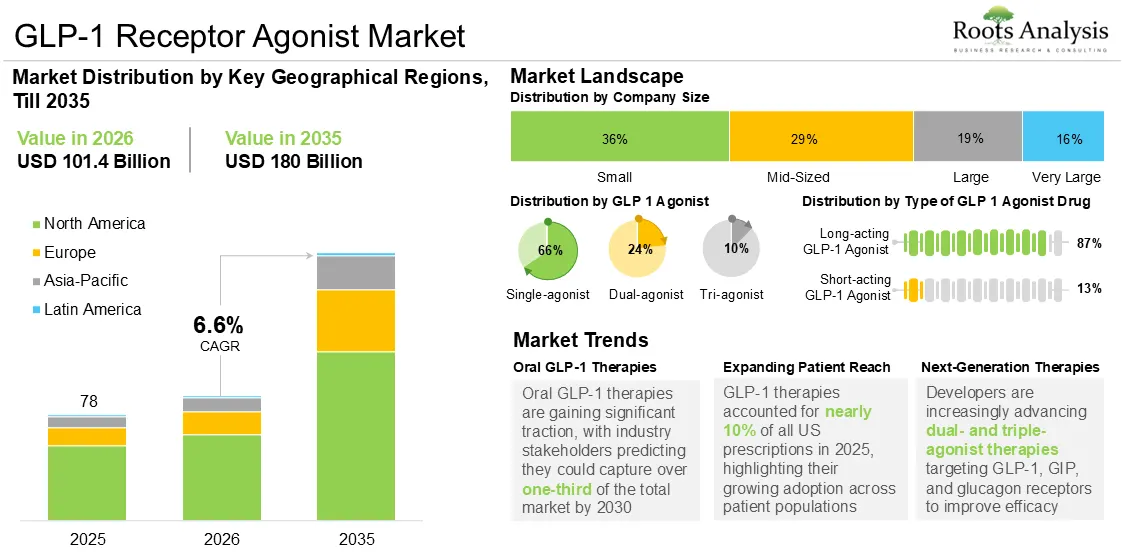
The GLP-1 receptor agonist market size, valued at USD 78 billion in 2025, is projected to reach USD 101.4 billion in 2026 and USD 180 billion by 2035, representing a CAGR of 6.6% during the forecast period 2026 to 2035. Growth is concentrated in three visible shifts: oral small-molecule formulations are gaining share against long-established injectable therapies, expanding patient populations beyond type 2 diabetes into obesity and adjacent metabolic conditions are pulling in new prescriber and payer categories, and developers are increasingly advancing dual- and triple-agonist molecules that target GLP-1 alongside GIP and glucagon receptors to improve efficacy per dose.
See What’s in the Full Report – Request Your Complimentary Insights!
Market Report: Key Takeaways
Market Size & Trends
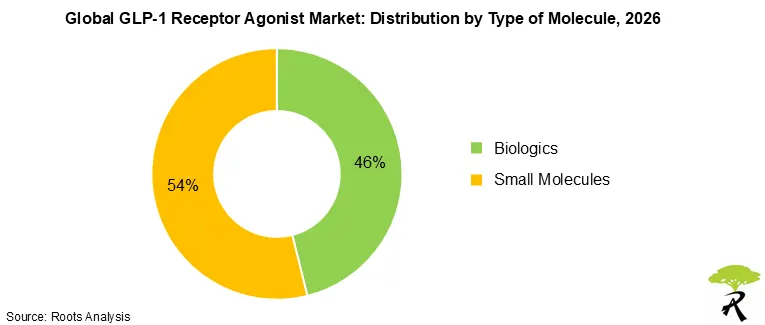
Small molecules hold the highest GLP-1 receptor agonist market share (nearly 55%), reflecting favorable manufacturing economics and formulation flexibility compared with biologic incretin therapies.
With respect to active compound used, semaglutide dominates the current market.
Based on the type of GLP-1 agonist drugs, long-acting formulations hold the largest share on the strength of reduced dosing frequency and improved adherence, a trend expected to persist through the forecast period.
In terms of GLP-1 agonist, single-agonist therapies hold the highest share (nearly 80%) of the market.
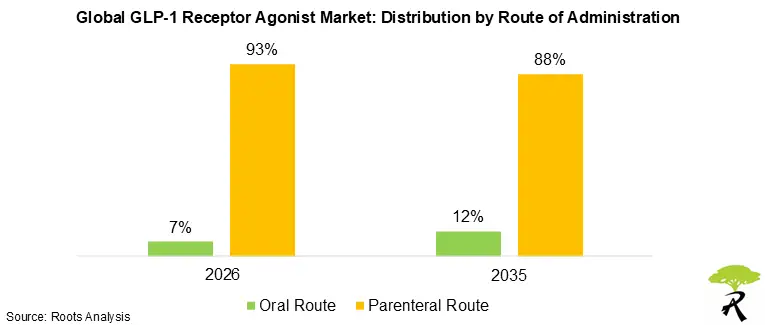
By route of administration, the parenteral (injectable) route still dominates current volume, though oral formulations are the fastest-growing route as delivery-technology advances reduce the administration burden for patients.
Based on the target indication, type 2 diabetes segment captures the largest share of the market, and the trend is unlikely to change in the future.
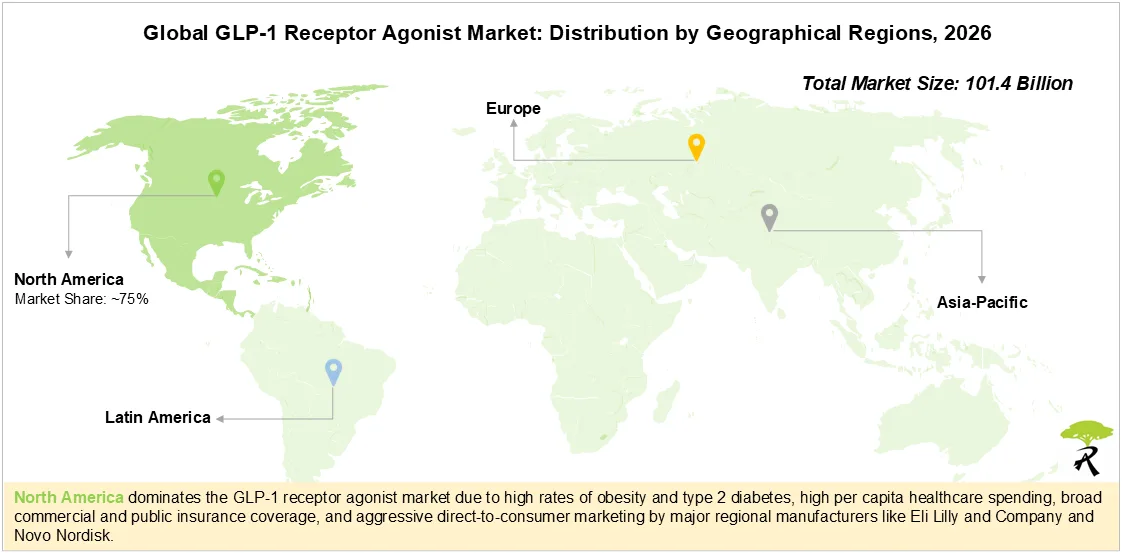
North America currently accounts for the largest market share, while Asia-Pacific is expected to grow at the fastest pace in the coming years.
Key Market Statistics
Market Size in 2026: $101.4 billion
Estimated Market Size in 2035: $180 billion
CAGR (2026-2035): 6.6%
Largest market, 2026: North America
Fastest growing region: Asia-Pacific
Market Introduction
GLP-1 receptor agonists are a class of medications built around the glucagon-like peptide-1 hormone pathway, originally developed to help regulate blood glucose in people with type 2 diabetes. Clinical evidence has since shown that several GLP-1 agonist drugs also support meaningful weight reduction and cardiovascular risk reduction, including a lower incidence of major adverse cardiovascular events (MACE) such as heart attack and stroke.
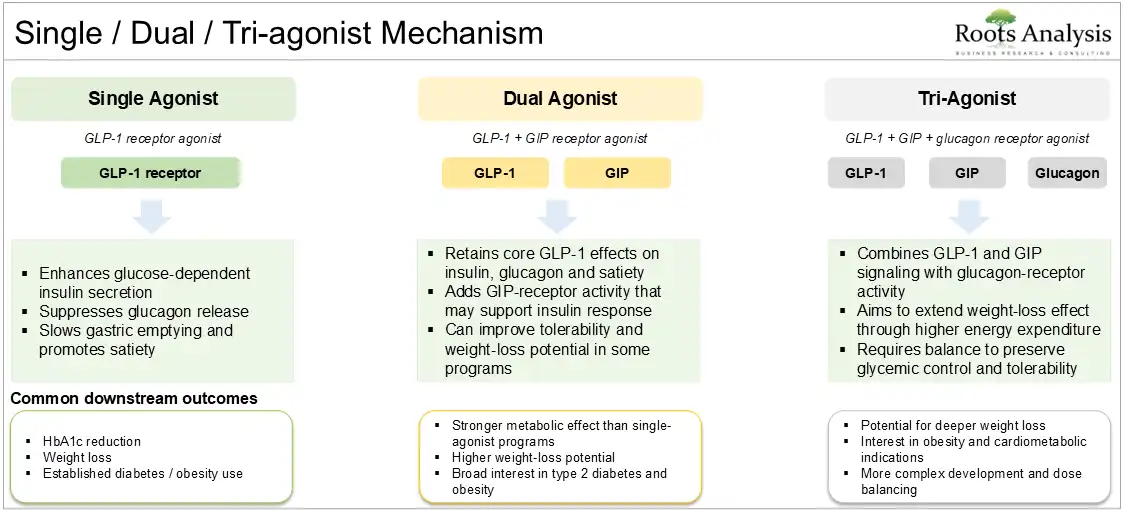
Mechanistically, GLP-1 is an incretin hormone released after food intake. GLP-1 receptor activation enhances glucose-dependent insulin secretion, suppresses inappropriate glucagon release, slows gastric emptying and promotes satiety. Together, these effects can improve blood glucose and HbA1c, reduce appetite and support body-weight reduction, while the magnitude of benefit varies by molecule, dose and patient population.
According to a study conducted by The Lancet, 42.4% of adult individuals in the US are obese, a population figure that helps explain the surge in consumer, media, and direct-to-consumer advertising attention this drug class has attracted in recent years. This has led to a surge in the demand for weight loss and type 2 diabetes treatment solutions, which is likely to spur innovation and market expansion in this domain.
As pharmaceutical companies work to meet rising demand for type 2 diabetes and body-weight management therapies, GLP-1 receptor agonists have emerged as one of the most active areas of drug development, supported by a growing volume of positive late-stage clinical evidence. Current research and development activity is concentrated on next-generation peptides, including oral small-molecule formulations that could reduce dependence on injectable delivery, and on combination therapies that pair GLP-1 activity with additional hormonal targets to broaden metabolic benefit per dose.
Recent regulatory activity has broadened the clinical and commercial scope of the GLP-1 class across type 2 diabetes, obesity and cardiovascular-risk reduction. In 2025, the FDA expanded the Rybelsus® label (developed by Novo Nordisk) to reduce the risk of major adverse cardiovascular events (MACE) in adults with type 2 diabetes who are at risk of these events. Teva launched an authorized generic of Vectoza (liraglutide 1.8 mg) in June 2024 for type 2 diabetes and cardiovascular-risk reduction; the FDA subsequently approved Teva’s generic referencing Saxenda in August 2025 for chronic weight management. These developments illustrate how label expansion and generic entry widens patient access while increasing competition across the class.
Your Business is Unique – Why Shouldn’t Your Report Be?
Key Players & Their Flagship GLP-1 Receptor Agonist Drug Products
The competitive landscape spans large multinational pharmaceutical companies and a growing set of biotech challengers advancing next-generation peptides. The table below summarizes four of the market's most prominent developers and their flagship GLP-1 receptor agonist drug products.
Company
Year of Establishment
Headquarters
Drug Name
Type
Primary Indication
Eli Lilly
1876
US
Tirzepatide (Mounjaro, Zepbound)
Dual GLP-1/GIP agonist
Type 2 Diabetes and Obesity
Novo Nordisk
1923
Denmark
Semaglutide (Ozempic, Wegovy, Rybelsus)
GLP-1 agonist
Type 2 Diabetes and Obesity
AstraZeneca
1999
UK
Exenatide (Bydureon BCise)
GLP-1 agonist
Type 2 Diabetes
Sanofi
1973
France
Efpeglenatide
Long-acting GLP-1
Type 2 Diabetes
The full report profiles a substantially longer list of companies active in this space, including AstraZeneca, Biolingus, Boehringer Ingelheim, D&D Pharmatech, Eli Lilly, Gmax Biopharm, Hanmi Pharmaceutical, Innogen, Novo Nordisk, PegBio, Pfizer, QL Biopharma, Roche, Sanofi, Sciwind Biosciences, Tonghua Dongbao Pharmaceutical, Viking Therapeutics, Vivani, and vTv Therapeutics, alongside a complete company list available in the full purchased report.
Market Segmentation
Based on the research, we have segmented the market into type of molecule, active compound used, type of GLP-1 agonist drugs, GLP-1 agonist, route of administration, target indication and geographical regions.
By Type of Molecule: Biologics, Small Molecules
By Active Compound Used: Dulaglutide, Liraglutide, Orforglipron, Retatrutide, Semaglutide, Survodutide, Tirzepatide, Other Active Compounds
By Type of GLP-1 Agonist Drugs: Long-acting GLP-1 Agonist, Short-acting GLP-1 Agonist
By GLP-1 Agonist: Single-agonist, Dual-agonist, Tri-agonist
By Geographical Regions: North America (US, Canada, Mexico), Europe (France, Germany, Italy, Spain, UK, Rest of Europe), Asia-Pacific (China, India, Japan, South Korea, New Zealand, Rest of the Asia-Pacific), Latin America (Argentina, Brazil)
GLP-1 Receptor Agonist Market Key Insights
What is the Market Opportunity for New Indications?
GLP-1 drugs target several indications, with type 2 diabetes being the first approved and primary indication for this drug class. In October 2025, the FDA approved Rybelsus (oral semaglutide) to reduce the risk of major adverse cardiovascular events in adults with type 2 diabetes at high cardiovascular risk. GLP-1 drugs are also under clinical evaluation for antidepressant effects. A group of researchers from various institutions in China has evaluated dulaglutide, marketed under the brand name Trulicity.
Rising GLP-1 uptake in patients seeking weight loss is also driving changes in food habits as the consumers seek healthier alternatives that meet nutritional needs. Major food companies such as Nestlé are seeking to capitalize on the opportunity created by changes in food preference for individuals taking GLP-1 peptides. In a recent interview with CNBC, Nestlé Former CEO Mark Schneider stated, “Nestlé will work on what we call companion products, products that really then address some of the specific consumer needs during weight loss treatment.” GLP-1 drugs are creating market opportunity not only for the biotech industry, but other industries as well.
What are the GLP-1 Receptor Agonist Market Restraints?
GLP-1 drugs, like other pharmaceutical products, will lose patent protection over time, with Novo Nordisk’s Victoza positioned as the first GLP-1 to face a U.S. patent expiry; the liraglutide (Victoza) patent expired in November 2024, and Teva Pharmaceuticals launched the first authorized generic in the US in June 2024, introducing a 1.8 mg dosage for glycemic control in adults with type 2 diabetes and for reducing major adverse cardiovascular events, while Sandoz also launched its generic in June 2024.
Semaglutide, the active ingredient in Ozempic, Wegovy, and Rybelsus, is set to lose US patent exclusivity on 20 March 2026. In October 2024, Mylan settled a US patent lawsuit with Novo Nordisk that grants Mylan and India-based Natco Pharma first-to-file rights for certain US generic semaglutide versions. Although generics typically put pressure on the prices, GLP-1 generics are expected to expand the overall market opportunity by improving affordability and availability across the drug class rather than simply eroding branded revenue.
How Are Digital Health and Distribution Channels Shaping Adoption?
GLP-1 commercialization is increasingly influenced by telemedicine, e-pharmacies, specialty and retail pharmacies, direct-to-patient platforms, employer benefits and public reimbursement programs. Digital health tools, including adherence reminders, remote follow-up and connected injection support, can help healthcare professionals monitor treatment persistence and address discontinuation caused by tolerability, affordability or administration burden.
Artificial intelligence is also being explored for patient identification, risk stratification, trial design, demand forecasting and adherence analytics. For pharmaceutical business-development and market-access teams, commercial success therefore depends not only on clinical efficacy but also on insurance coverage, prior-authorization criteria, distribution-channel reach, product availability and the ability to support patients’ throughout long-term therapy.
Recent Developments
In June 2026, AstraZeneca advanced its oral small-molecule GLP-1 receptor agonist elecoglipron into a comprehensive Phase III program, following positive Phase IIb results showing significant weight loss and glycemic improvements.
In June 2026, the US Medicare program introduced an 18-month pilot initiative called GLP-1 Bridge, offering obesity medications such as Wegovy and Zepbound at approximately USD 50 per month.
In April 2026, Eli Lilly received FDA approval for orforglipron (Foundayo), its oral GLP-1 receptor agonist, for weight management in adults with obesity or those who are overweight with comorbidities.
In March 2026, Structure Therapeutics reported positive Phase II results for its oral GLP-1 agonist aleniglipron, achieving substantial weight loss and advancing toward Phase III.
In December 2025, Novo Nordisk received FDA approval for its oral semaglutide Wegovy pill (25 mg) for weight management, the first oral GLP-1 approved for this indication, with commercial rollout beginning in early 2026.
Methodology and Industry Expert Interviews
The findings in this report were developed through a structured methodology combining secondary research, proprietary databases and primary interviews. Secondary research included company disclosures, regulatory databases, clinical-trial registries, peer-reviewed publications, patent records, pricing and reimbursement sources, and relevant market-access information. The resulting assumptions were triangulated against product approvals, pipeline progress, sales trends, formulation mix, regional access conditions and stakeholder interviews.
Professor Jura Liaukonyte (working as Associate Professor in the Charles H. Dyson School of Applied Economics and Management at Cornell University), stated that, “The pattern is less about switching to ‘better’ foods and more about simply buying less food. As GLP-1 adoption grows and new applications come to light, it could have sweeping impacts for both health outcomes and the economy. This shift could have notable implications for fast-moving consumer goods (FMCG) companies and food producers more broadly.”
Discussions with multiple stakeholders in this domain influenced the opinions and insights presented in this study. The market report includes transcripts of the following other third-party discussions:
Chief Executive Officer, Large Organization, US
Associate Professor, Large Organization, US
Chief Scientific Officer, Large Organization, UK
Chief Commercial Officer, Mid-sized Organization, UK
Senior Account Executive, Large Organization, US
Chief Executive Officer, Large Organization, US
Chief Executive Officer, Large Organization, Denmark
Chief Scientific Adviser for Research, Large Organization, Denmark
Chief Executive Officer, Mid-sized Organization, India
Chief Medical Officer, Mid-sized Organization, US
Pay Only for What You Need – The Best Way to Optimize
Market Share Insights
Which Type of Molecule Captures the Largest GLP-1 Receptor Agonist Market Share?
Small molecules currently account for the largest share (nearly 55%) of the market, driven by favorable drug development economics. Compared with biologics, small molecules offer better formulation flexibility, lower production complexity, and cost-efficient large-scale manufacturing. In addition, their well-established development pathways and compatibility with conventional pharmaceutical production infrastructure have encouraged significant industry investment toward the development and commercialization of small molecule GLP-1 therapies. Biologics are nonetheless expected to see significant growth during the forecast period, supported by strong clinical performance in glycemic control, weight management, and cardiovascular risk reduction, and by continued innovation in long-acting and next-generation incretin formulations.
Which Active Compound is Anticipated to Capture the Largest Share of the GLP-1 Receptor Agonist Market?
Based on active compound used, the market is segmented into dulaglutide, liraglutide, orforglipron, retatrutide, semaglutide, survodutide, tirzepatide, and other active compounds. Semaglutide currently holds the largest share, primarily driven by its broad commercial success across multiple indications including type 2 diabetes and obesity. Unlike many earlier GLP-1 therapies that were primarily positioned for diabetes management, semaglutide has significantly expanded the commercial potential of the drug class through its strong clinical outcomes in weight reduction. Availability of semaglutide across multiple formulations has further strengthened its market penetration and contributed to its dominance within the market.
Retatrutide and survodutide are expected to post the highest growth during the forecast period, driven by rising interest in next-generation incretin therapies capable of delivering enhanced efficacy across multiple metabolic disorders beyond traditional glucose management.
Which type of GLP-1 Agonist Dominates?
Long-acting GLP-1 agonists currently hold the largest share of the market, owing to their ability to provide sustained receptor activation through less frequent dosing schedules that improves treatment adherence and supports long-term disease management. Long-acting GLP-1 agonists offer relatively greater convenience for patients and healthcare providers, making them particularly suitable for chronic conditions that require continuous treatment.
Short-acting GLP-1 agonists are nonetheless expected to see notable growth, driven by ongoing efforts to expand treatment options for diverse patient populations and clinical scenarios. Such therapies, in certain settings, may offer greater dosing flexibility and enable more individualized treatment approaches.
Amongst Single-agonist, Dual-agonist, and Tri-agonist Therapies, Which Segment Holds the Largest Share in the GLP-1 Receptor Agonist Market?
Single-agonist therapies currently hold close to 80% of the market, primarily driven by the presence of several commercially established single-agonist GLP-1 therapies that have been widely adopted across treatment settings. These therapies entered the market earlier than most dual- and tri-agonist candidates, enabling them to build physician familiarity, generate extensive clinical evidence, and secure broad market access across major healthcare systems.
Tri-agonist therapies are expected to witness the fastest growth, driven by increasing interest in next-generation therapies designed to simultaneously target multiple metabolic pathways. By engaging additional hormonal mechanisms beyond GLP-1 receptor activation, these therapies have demonstrated the potential to deliver enhanced weight reduction and broader metabolic benefits.
For developers and investors reading this market, multi-agonist therapies represent the segment where the largest incremental clinical and commercial value is likely to be created over the 2026 to 2035 forecast window. This report tracks pipeline progress across all three agonist categories each edition, so buyers can monitor exactly how quickly that shift moves from forecast to realized revenue.
Is Oral Catching up with the Parenteral Route?
The parenteral segment currently accounts for 93% of the overall revenue, a share attributable to the long-established clinical use of injectable GLP-1 therapies and the availability of several commercially available products across indications such diabetes and obesity. Parenteral administration also enables the delivery of peptide-based therapies directly into systemic circulation, improving drug absorption and helping maintain consistent therapeutic activity.
The oral route, while starting from a smaller base of roughly 7% in 2026, is forecast to be the fastest-growing route, reaching an estimated 12% share by 2035 as patient preference for non-invasive treatment and advances in oral drug-delivery technology continue to reduce the administration burden for patients reluctant to use injectable therapies.
Which Target Indication Holds the Largest Share of the GLP-1 Receptor Agonist Market?
Type 2 diabetes currently accounts for the largest share of the market, driven by the established use of GLP-1 receptor agonists in diabetes management and the extensive clinical evidence supporting their efficacy in glycemic control. GLP-1 therapies now represent an integral component of type 2 diabetes treatment regimens due to their ability to improve blood glucose regulation. In addition, they also provide benefits such as weight reduction and cardiovascular risk reduction.
Non-alcoholic steatohepatitis is expected to be the fastest-growing indication over the forecast period as evidence linking GLP-1–mediated weight reduction and metabolic improvement to liver-disease outcomes continues to develop.
Regional Analysis
North America Dominates the Market
North America captures approximately 75% of the GLP-1 receptor agonist market. The region’s leadership is supported by the high prevalence of type 2 diabetes and obesity, established healthcare infrastructure, strong physicians awareness, broad commercial availability and comparatively favorable reimbursement for eligible patients. In 2025, Eli Lilly announced a USD 27 billion US manufacturing build-out across multiple sites to expand medicine supply and support rising demand.
Asia-Pacific to Post Fastest Regional Growth
The rapid urbanization and rising middle-class income in key Asia-Pacific countries, such as China, India, and South Korea, are accelerating market growth in the region. Governments are actively supporting disease-management infrastructure through public-awareness campaigns and expanding reimbursement schemes, while pharmaceutical companies are investing in local manufacturing capacity and new therapy launches. The rise of e-commerce and telemedicine platforms in markets like China and India is also making GLP-1 treatment access considerably easier for patients outside major urban centers.
Key Players Profiled
Report Deliverables and Customization
Alongside the core market report, clients receive complimentary Excel data packs covering market landscape analysis, partnerships and collaborations analysis, company competitiveness analysis, funding analysis, clinical trial analysis, demand analysis, pricing analysis, patent analysis, market size and opportunity analysis. A complimentary PowerPoint presentation summarizing the full report is also included, and 15% free customization scope is available on request.
Report Authorship
This report was authored by Simriti Gupta, member of the Roots Analysis healthcare and pharmaceutical research practice. Her work focuses on drug discovery and development, therapeutic-market assessment, competitive intelligence, clinical-pipeline analysis and market forecasting.
Independence and Non-Affiliation
This report is an independent work of market research and analysis published by Roots Analysis. It is not affiliated with, sponsored by, endorsed by, or reviewed by Eli Lilly, Novo Nordisk, AstraZeneca, Sanofi, Pfizer, Merck, or any other pharmaceutical company, drug brand, or regulatory body referenced within it. No content in this report should be construed as medical advice. Roots Analysis maintains its own proprietary primary research process, and does not receive compensation from any company profiled within the report, in exchange for inclusion or favorable characterization.
Methodology
Research Methodology
Overview
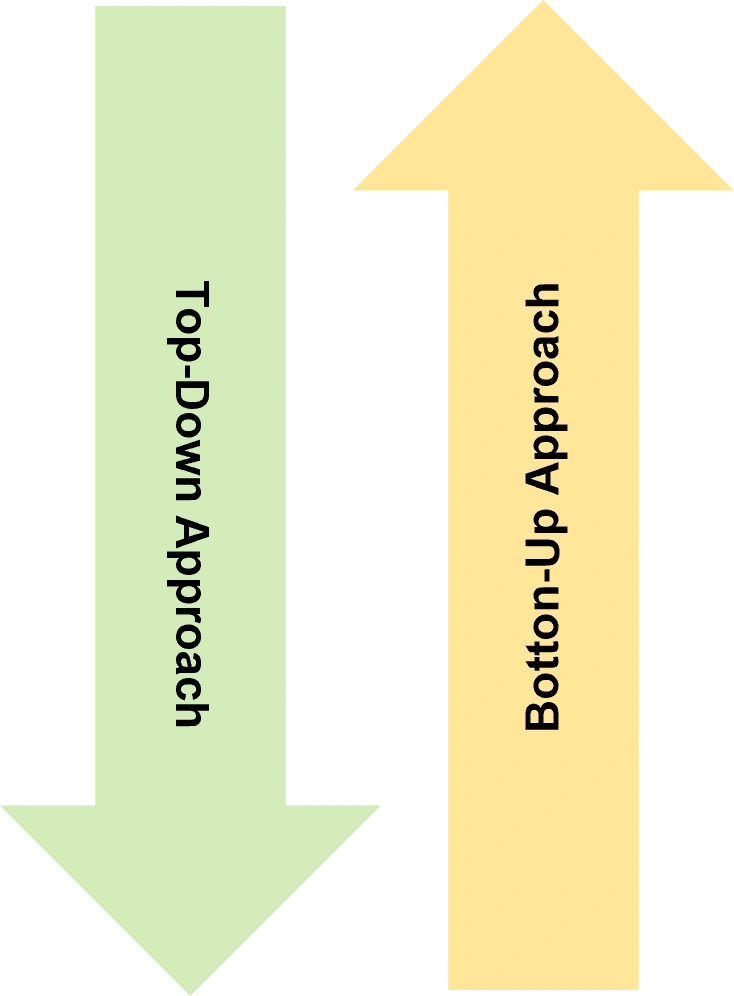
Our market forecasting methodology follows a holistic approach (for both top-down and bottom-up techniques), combining statistical models, in-depth market research, demand analysis, and expert insights to deliver accurate predictions of future trends and outcomes. Market size estimation is derived through a mix of secondary and primary research. To ensure accuracy and reliability, all findings are rigorously validated through data triangulation, aligning insights from multiple sources to strengthen the credibility and precision of the overall market and segment-level forecasts.
Conduct comprehensive industry analysis to assess TAM using validated secondary sources
Segment market by region or application to determine relevant sub-industry scope / in order to calculate the serviceable addressable market
Calculate serviceable obtainable market by applying penetration rates or adoption assumptions
Assess the historical information on growth patterns / CAGR for realistic market opportunity sizing
Calculate actual market using segmentation and penetration data, and projected its growth during the forecast period
Validate final estimates via scenario-based analysis and expert opinions gathered through extensive primary and secondary research
Identify the key component, such as products / drugs / technologies across the sector that are to be forecasted, using market databases
Estimate the average units / volumes per component by collecting primary and secondary data by leveraging information on historical industry activity
Assess the historical information on prices, adoption and penetration data, and growth patterns / CAGR for realistic market opportunity sizing
Calculate total market size by multiplying volumetric estimates with average costs / prices per component, and projected its growth during the forecast period
Validate final estimates via scenario-based analysis and expert opinions gathered through extensive primary and secondary research
Data Collection: Source and Methods
Secondary Research
In this research process, various secondary sources are referred to identify and collect information regarding the study. The secondary sources include annual reports, press releases, investor presentations, forums, certified publications, whitepapers, government, and regulatory bodies (like FDA, WHO, WTO, EPA). The secondary research is mainly used to identify reliable publicly available information sources, studying various market trends, key drivers / restraints to generate insightful conclusions, and robust data validation.
Primary Research
In the primary research process, we follow a structured approach to ensure comprehensive stakeholder engagement and actionable insights. We conduct detailed research to identify relevant stakeholders (both demand and supply side) and setup multi-channel interviews, utilizing emails, LinkedIn, direct calls, and other channels to schedule the interviews. We then conduct in-depth interviews, preparing detailed transcripts, and tabulate responses for further analysis. The primary sources included various industry experts, including Chief Executive Officers (CEOs), Vice Presidents (VPs), marketing directors, technology and innovation directors, and related key executives from various key companies and organizations operating in the respective market.
Market Sizing and Analysis
Our market reports provide comprehensive market sizing and analysis, methodologically advancing from Total Addressable Market (TAM) to Serviceable Addressable Market (SAM) and Capturable Addressable Market (CAM). We integrate key growth drivers, including supply-demand dynamics, new market entrants, economic conditions, technological advancements, and capital requirements for deep insights into expansion factors. Our structured TAM, SAM, and CAM framework delivers thorough, actionable market reports to empower strategic decision-making and market potential growth.
Market Assessment Framework: From Total Potential to Achievable Share
Total Addressable Market (TAM)
Represents the total potential revenue opportunity if a company captures 100% market share for its product or service.
Serviceable Addressable Market (SAM)
The portion of TAM that a company can reach, considering its geographic limits, products, regulations, and market constraints.
Serviceable Obtainable Market (SOM)
The realistic segment of SAM that a company can capture based on its market presence, competitive position, and capabilities.
Currently Acquired Market (CAM)
The current market share held by a company, used to benchmark performance and guide strategies for growth & expansion.
Example Factors Influencing Market Growth Potential
Competitive Landscape
Assessing key market players, competitor strategies and market positioning.
Technological Advancements
Evaluating impact of new technologies on market evolution and disruption.
Economic Indicators
Assessing influence of metrics, such as GDP, trade dynamics, inflation, and consumer spending.
Market Demand & Supply
Analyzing forces and external factors driving customer needs and product supply.
Market Entry Barriers
Understanding obstacles for new entrants, such as regulations and capital and technical requirements.
Historical Trends & Growth Rates
Considering historical growth rate patterns, product sale revenues and adoption trends.
Our forecast methodology integrates a rigorous hybrid approach combining top-down market sizing with detailed bottom-up validation. This proven method delivers precise market size estimates, reliable growth rates, and credible CAGR projections that stakeholders can trust for strategic decision-making in pharma and biotech outsourcing. The methodology features extensive primary research through in-depth stakeholder interviews with executives from contract service organizations (CMO/CDMO/CRO), biopharma sponsors, biotechnology firms, and key opinion leaders. These insights are complemented by comprehensive secondary analysis of FDA and EMA regulatory filings, clinical trial pipeline data, historical revenue trends, annual reports, competitive intelligence, and industry benchmarks. Moreover, data triangulation across multiple sources validates critical trends, including patient population growth and obesity / diabetes prevalence, therapeutic-area demand drivers, evolving clinical evidence and treatment paradigms, modality- and formulation-specific technology adoption (for instance long-acting injectables, oral and peptide-stabilization platforms), probability of technical and regulatory success for GLP-1 candidates, and competitive dynamics across branded, biosimilar, and combination-product pipelines. Sensitivity analysis and scenario modeling further enhance forecast robustness against regulatory changes, technological breakthroughs, and market disruptions. This industry-validated approach ensures high-confidence, actionable insights. It positions expert service partners at the forefront of biopharmaceutical market intelligence, empowering informed investment, capacity planning, and competitive strategies in the rapidly evolving pharma and biotech outsourcing landscape.
Data Validation and Quality Assurance
We deliver verified industry forecasts with 100% accuracy in all market size, CAGR, and growth projections through rigorous market forecast validation processes. We cross-verify data from 100+ trusted sources for precise market size accuracy in our fact-checked market research reports, provide exclusive inputs from 500+ industry experts, ensuring CAGR validation and reliable projections which are backed by 200+ years of sector expertise for benchmarked, future-proof verified industry forecasts.
Market Mapping
via
Secondary Research
Covers credible, high-quality data sources:
Paid Databases: Bloomberg, Factiva, Dun&Bradstreet (D&B) Hoovers, Thomson Reuters Eikon and Other Prominent Databases
Literature Search: Annual Reports, Company Websites, Financial Filings, Investor Presentations, White Papers etc
Primary Research
through
Stakeholder Interviews
Includes extensive primary research via:
KOL Interviews: In-depth conversations with CXOs, Founders, Director, VPs and other Senior Management stakeholders
Surveys / Polls: Widens reach and reveals insights into unmet needs, customer preferences and emerging market opportunities
Strategic Interpretation
with
Rootsight
Generates a holistic ecosystem view:
Influencing Factors Analysis
Competitive Landscape & Key Players
Drivers and Restraints Mapping
Opportunities and Challenges Assessment
Regional & Segment Level Insights
Historical Market Benchmarking
Analyst Interpretation & Forecast Refinement
Data Triangulation
and
Validation
Sense-checks and finalization of output / recommendations:
Multi-angle Forecast
Scenario Planning / Testing
Segment-specific Models
Econometric Models
Extensive validation via multiple approaches (listed below)
Insight Delivery
& Strategic
Recommendations
Comprehensive set of deliverables:
Market Size Estimates
Informed Future Growth Projections
Actionable Insights Tailored by Region, Segment, and Timeline
Model Walkthrough via Workshops
Audio podcasts
12-month unrestricted support
Complimentary upgrade to the next edition
Customization Options
At Roots Analysis, we pride ourselves on offering tailored market research solutions that adapt to your unique business needs. Our extensive customization options ensure that you receive insights that are not only relevant but also actionable. Upon purchase, clients can ask for 10% customization on a variety of modules.
01
Competitive
Intelligence
Landscape Analysis
Product / Portfolio Evaluation
Relative Competitive Assessment
Company Profiles
02
Strategy and Growth
Assessment
Value Creation Framework
Business Model Assessment
Blue Ocean Strategy
Go-no-go Framework
03
Market Potential
Assessment
Opportunity Analysis
Multivariate Sensitivity Analysis
Time Series Analysis
Region / Country wise Analysis
04
Product
Intelligence
Brand Positioning Analysis
Product Launch Strategy
Lifecycle Management
Success Protocol Analysis
05
Supplier Identification /
Assessment
Supplier Landscape Analysis
Peer Benchmarking
Vendor Selection Framework
Risk Assessment
06
Opinion Based
Assessment
Video / Telephonic Interviews
Online Surveys
Focused Group Discussions
Customer Feedback Analysis
07
Trends
Assessment
Partnerships and Collaborations
Patent Analysis
Capability Expansion Analysis
Clinical Trial Analysis
08
Merger & Acquisition and
Deal Trends
M&A Evolution
Financial Analysis
Start-up Valuation
Deal Multiple Analysis
09
Cost
Models
Total Cost of Ownership
CAPEX and OPEX Analysis
Make-vs-Buy Framework
NPV and IRR Analysis
10
Financial and
Investment Analysis
Assessment of Funding Models
Funding Life Cycle Analysis
Due Diligence
Exits / Profitability Assessment
11
Medtech
Intelligence
Demand Forecasting
Licensing Deal Assessment
Competitive Benchmarking
Value Chain Analysis
12
IP
Intelligence
Pockets of Innovation
White Space Analysis
CPC Analysis
Patent Valuation
Describe Usage
How many people will be using this report?
To help us serve you better, please select the best option that describes the usage of this report
Request Quote
Thank you for submitting the details. Your message has been sent to the relevant team. One of our team members will shortly email you the relevant quotation. For any queries, please feel free to reach out to us at support@rootsanalysis.com
Roots Analysis Customer Support
Looking for Insights that Match Your Needs?
LET’S CREATE SOLUTIONS THAT TRULY MATTER TO YOUR BUSINESS.
Book a Free Report Workshop Session to:
Get a guided tour of the actual report
Share your specific needs
Discuss the customizations options for you
GLP-1 Receptor Agonist Market 2nd Edition, 2026 to 2035
Report Code: 4576 Format: PDF Request Type: Get Your Free Sample
Request A Sample
Stay informed about the latest trends and insights that are shaping your field.
GLP-1 Receptor Agonist Market 2nd Edition, 2026 to 2035
Report Code: 4576 Format: PDF Request Type: Request a Quote
Request A Quote
Stay informed about the latest trends and insights that are shaping your field.
GLP-1 Receptor Agonist Market 2nd Edition, 2026 to 2035
Report Code: 4576 Format: PDF Request Type: Customization
Get Custom Report
Stay informed about the latest trends and insights that are shaping your field.
GLP-1 Receptor Agonist Market 2nd Edition, 2026 to 2035
Report Code: 4576 Format: PDF Request Type: Speak with Analyst
Speak With Our Analyst
Book a Preview Call
Select a Date
GLP-1 Receptor Agonist Market 2nd Edition, 2026 to 2035
Report Code: 4576 Format: PDF Request Type: Customization
Request Sectional Pricing
Stay informed about the latest trends and insights that are shaping your field.
Thank You
We have received your request. Someone from our team will contact you soon.
Thank You
Thank you for contacting Roots Analysis. Our team will get back to you shortly.


 Download Free Sample
 Buy Now